Metal Injection Molding Market Outlook:
Metal Injection Molding Market size was valued at USD 7.4 billion in 2026 and is projected to reach USD 18.6 billion by the end of 2036, registering around 9.7% CAGR during the forecast period, i.e., 2027-2036. In 2027, the industry size of metal injection molding is assessed at USD 8.1 billion.
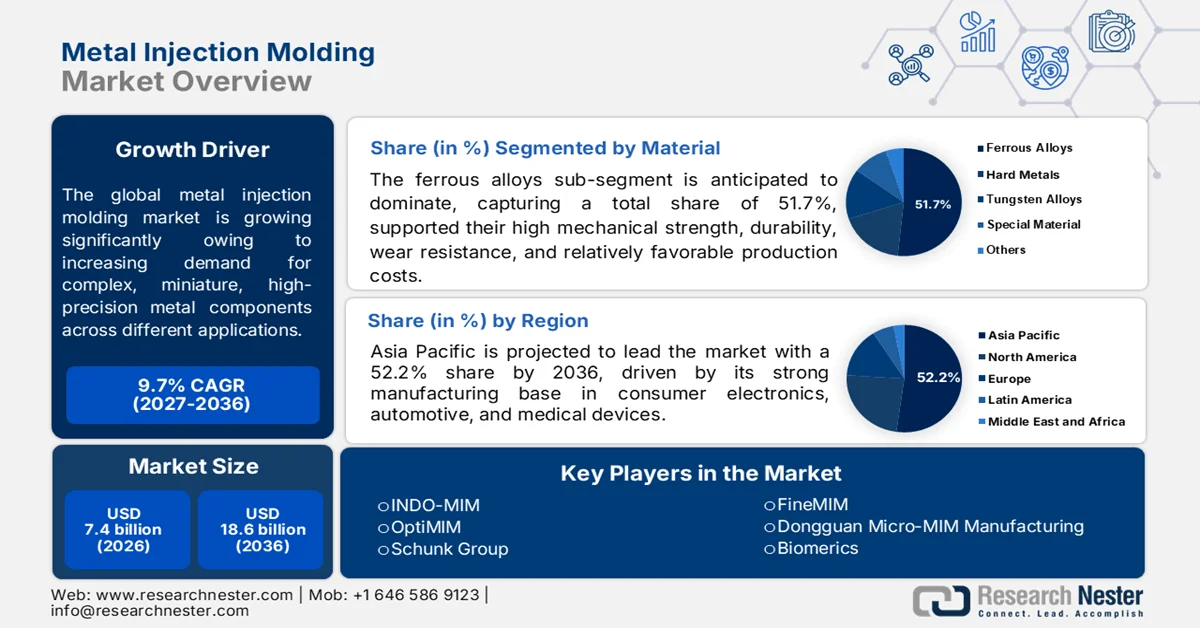
The metal injection molding market is supported by increasing demand for complex, miniature, high-precision metal components across automotive, electric mobility, medical devices, consumer electronics, industrial equipment, aerospace, and defense applications. Industry trends are moving toward micro-MIM, higher-density and tighter-tolerance components, use of stainless steel, soft magnetic materials, and titanium and specialty alloys. In this context, the World Steel Association in April 2025 stated that stainless steel melt shop production rose 7% year-on-year in 2024, and it surpassed 62.6 million metric tons globally. This increase reflects continued growth in worldwide stainless-steel manufacturing when compared with 2023, thus elevating the growth potential of the metal injection molding industry.
Global Stainless Steel Melt Shop Production by Region
|
Region |
2023 Production (000 metric tons) |
2024 Production (000 metric tons) |
Growth 2024 vs. 2023 |
|
Europe |
5,997 |
6,088 |
1.5% |
|
U.S. |
1,824 |
1,950 |
6.9% |
|
China |
36,676 |
39,441 |
7.5% |
|
Asia w/o China & S. Korea |
6,880 |
7,322 |
6.4% |
|
Others |
7,163 |
7,820 |
9.2% |
|
Global Total |
58,539 |
62,621 |
7.0% |
Source: World Steel Association
Furthermore, the supply chain in the market is becoming more integrated as producers are looking for control over powder sourcing, feedstock preparation, molding, debinding, sintering, finishing, inspection, and component qualification. In this context, stainless steel is considered a major feedstock category, and demand is expanding for titanium, nickel-based, cobalt-chrome, and soft magnetic materials. U.S. Geological Survey stated that U.S. raw steel production reached 82 million metric tons in 2025. It also mentioned that steel production was concentrated in Ohio, Pennsylvania, and Texas, whereas construction accounted for the largest share of net steel shipments at 31%.
Global Steel Production by Country, 2024-2025 (Million Metric Tons)
|
Country/Region |
Raw Steel 2024 |
Raw Steel 2025 |
|
U.S. |
79.5 |
82 |
|
Brazil |
34 |
35 |
|
China |
1,010 |
980 |
|
Germany |
37 |
38 |
|
India |
150 |
160 |
|
Iran |
31 |
32 |
|
Japan |
84 |
81 |
|
South Korea |
64 |
60 |
|
Russia |
71 |
65 |
|
Türkiye |
37 |
37 |
|
Vietnam |
22 |
23 |
|
Other countries |
269 |
280 |
|
World total (rounded) |
1,880 |
1,900 |
Source: USGS
Key Metal Injection Molding Market Insights Summary:
Regional Highlights:
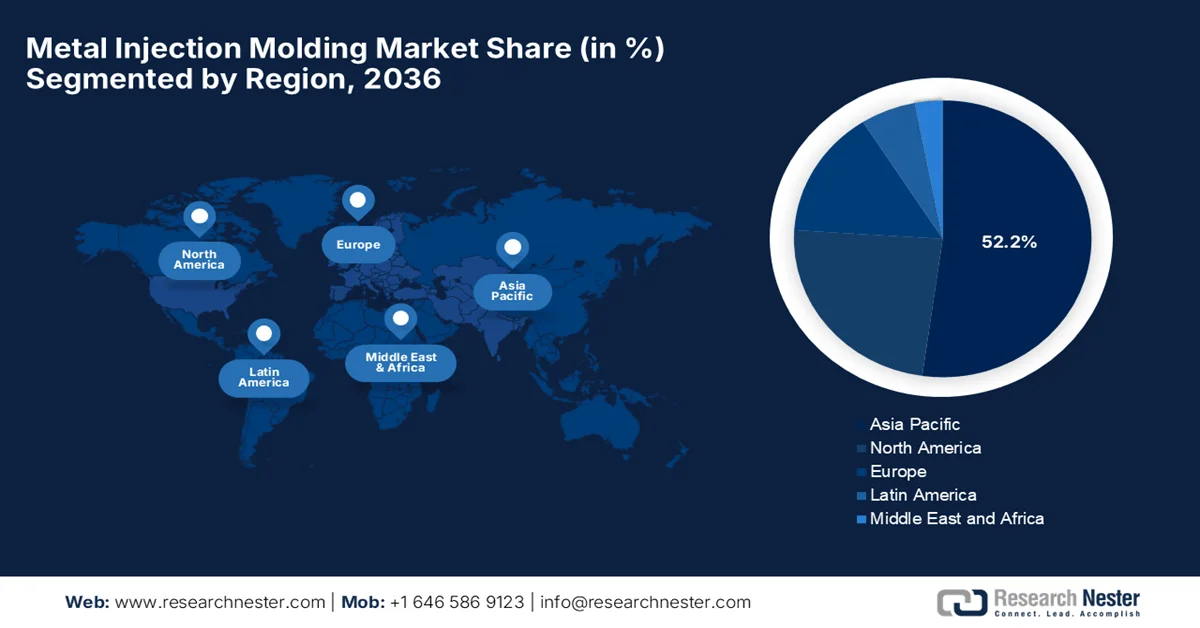
- Asia Pacific is projected to command a 52.2% share of the metal injection molding market during the forecast timeframe, fueled by its strong manufacturing footprint across consumer electronics, automotive production, and medical devices
- Europe is expected to expand at a considerable rate through 2036, supported by greater industrial automation, stringent environmental sustainability standards, and the growing adoption of advanced manufacturing technologies
- The metal injection molding market in the U.S. accounts for 75.7% of the share in North America, which is driven by the strong medical-device, aerospace and defense, automotive, and advanced manufacturing industries
- The market in Japan accounts for 20.2% of the share in the Asia Pacific, owing to the strong demand for high-accuracy, miniature, and complex metal components
Segment Insights:
- Ferrous alloys are projected to account for a dominant 51.7% share of metal injection molding market by 2036, owing to their high mechanical strength, durability, wear resistance, and relatively favorable production costs
- The automotive segment is positioned for lucrative growth during 2027-2036, propelled by increasing demand for lightweight, compact, and highly precise components and the adoption of metal injection molding for complex geometries at high production volumes
Key Growth Trends:
- Expanding medical device industry
- Aerospace and defense modernization
Major Challenges:
- Complex process control and quality requirements
- Material and design limitations
Key Players: INDO-MIM, OptiMIM, Schunk Group, FineMIM, Dongguan Micro-MIM Manufacturing, Biomerics.
Global Metal Injection Molding Market Forecast and Regional Outlook:
Market Size & Growth Projections:
- 2026 Market Size: USD 7.4 billion
- 2027 Market Size: USD 8.1 billion
- Projected Market Size: USD 18.6 billion by 2036
- Growth Forecasts: 9.7% CAGR (2027-2036)
Key Regional Dynamics:
- Largest Region: Asia Pacific (52.2% Share by 2036)
- Fastest Growing Region: Asia Pacific
- Dominating Countries: China, Japan, South Korea, United States, Germany
- Emerging Countries: India, Taiwan, Mexico, Italy, Canada
Last updated on : 25 August, 2026
Metal Injection Molding Market - Growth Drivers and Challenges
Growth Drivers
- Expanding medical device industry: The worldwide surge in terms of minimally invasive surgeries is fueling adoption in the market. Medical device manufacturers depend on the technology to produce ultra-miniature, biocompatible components such as surgical graspers, biopsy forceps, and orthopedic implants. In January 2025, the National Institutes of Health (NIH) stated that a study consisting of 408 U.S. hospitals found that 38% of them introduced robotic-assisted surgery, wherein MIS rates increased from 60.5% to 65.8% in those hospitals. It also outlined that the relative MIS rate increased from 1.08 to 1.15, P<0.01 after RAS introduction, indicating huge MIS adoption.
- Aerospace and defense modernization: Military and commercial aerospace sectors necessitate lightweight, ultra-high-strength components that have the potential to withstand extreme environments. In this context, metal injection molding produces complex, flight-critical parts such as locking mechanisms, missile guidance hardware, and drone components. Testifying to this, NIH in August 2023 disclosed that a rapid tooling method for metal injection molding using aluminum-filled epoxy resin molds was developed. It also underscores that this approach reduced mold manufacturing costs by around 30.4% and manufacturing time by 30.3% when compared with conventional steel molds, thus positively benefiting the market globally.
Challenges
- Complex process control and quality requirements: Maintaining consistent quality in the entire MIM process is highly challenging as it involves several interdependent stages, i.e., feedstock preparation, injection molding, debinding, and sintering. Any type of variation in temperature, pressure, binder removal, or sintering conditions can cause shrinkage, warpage, cracking, density variations, as well as dimensional defects. Therefore, achieving tight tolerances requires advanced process monitoring, controlled production environments. These requirements can increase manufacturing complexity and operating costs, restricting growth of the market. Furthermore, demand from medical, aerospace, automotive, and electronics industries for precise components also increases quality requirements.
- Material and design limitations: MIM supports numerous metals and complex geometries, but it still has certain material and design limitations that are causing restrictions to market expansion. Not all metals and alloys are suitable because materials should have the required powder characteristics, flow properties, and sintering behavior. Apart from these, designers need to account for significant shrinkage during debinding and sintering, which in turn can complicate dimensional control. Large components, thick sections, and unsuitable wall thicknesses might be difficult or uneconomical to manufacture using MIM. In this context, component development requires close collaboration between designers, material specialists, and manufacturers in the market.
Metal Injection Molding Market Size and Forecast:
| Report Attribute | Details |
|---|---|
|
Base Year |
2026 |
|
Forecast Period |
2027-2036 |
|
CAGR |
9.7% |
|
Base Year Market Size (2026) |
USD 7.4 billion |
|
Forecast Year Market Size (2036) |
USD 18.6 billion |
|
Regional Scope |
|
Metal Injection Molding Market Segmentation:
Material Segment Analysis
On the basis of material, the ferrous alloys sub-segment is anticipated to dominate the metal injection molding market, capturing a total share of 51.7% by 2036. This dominance is largely supported by growing preference due to their high mechanical strength, durability, wear resistance, and relatively favorable production costs. Their ability to withstand demanding operating conditions makes them highly suitable for manufacturing precision components. In this context, USGS stated that global production totaled around 44.5 million metric tons of bulk ferroalloys and 18.4 million metric tons of noble ferroalloys in 2022. It also mentions that the U.S. bulk ferroalloy production was 398,000 metric tons in 2022, whereas the reported consumption reached 1.03 million metric tons.
Industry Segment Analysis
The automotive segment under the industry segment is forecasted to display lucrative growth opportunities in the market from 2027 to 2036. The sub-segment’s growth can be ascribed to the increasing demand for lightweight, compact, and highly precise components in modern vehicles, coupled with the growing adoption of metal injection molding for manufacturing complex geometries at high production volumes. In addition, the technology enables manufacturers to achieve near-net-shape components with reduced material wastage and lower machining requirements, which in turn supports cost-efficient automotive production. The rising integration of advanced components in electric vehicles, powertrain systems, fuel-injection systems, sensors, and electronic assemblies is creating significant opportunities for MIM components.
Equipment Type Segment Analysis
The injection molding machines sub-segment is expected to hold a commanding share in the market during the stipulated timeframe. The increasing demand for automated, high-precision, and high-throughput manufacturing equipment that is capable of producing complex metal components at scale is the main fueling factor for this growth. The rising adoption of advanced injection molding systems with improved process control, energy efficiency, and automation is enabling manufacturers to enhance productivity. In July 2025, ARBURG and RNA developed an automated insert-molding cell for R a Labone to increase production of HGV tyre-pressure sensor housings. This upgraded cell can produce around 50,000 parts per week, helping meet increased demand, thus denoting a wider segment scope.
Our in-depth analysis of the market includes the following segments:
|
Segment |
Subsegments |
|
Material |
|
|
Industry |
|
|
Equipment Type |
|

Vishnu Nair
Head - Global Business DevelopmentCustomize this report to your requirements — connect with our consultant for personalized insights and options.
Metal Injection Molding Market - Regional Analysis
APAC Market Insights
Asia Pacific metal injection molding market is forecasted to attain the highest share of 52.2% during the assessed timeframe. The region’s upliftment in this sector is largely propelled by its strong manufacturing footprint in consumer electronics, automotive production, and medical devices. In addition, key industrial hubs are driving regional expansion due to the heavy concentration of smartphone and automotive component assembly lines, which require high-volume, micro-sized precision parts. In June 2023, Micron announced a major semiconductor assembly and testing facility in Gujarat to manufacture DRAM and NAND products for India and global markets. This project involves substantial investment, government support, and strengthening India’s developing semiconductor ecosystem, thus heightening demand for metal injection molding.
The nation’s unparalleled manufacturing ecosystem and the presence of major consumer electronics giants are boosting growth in the China metal injection molding market. The country’s market is primarily supported by a mature and self-sustaining supply chain, which boasts abundant domestic production of carbonyl iron and stainless-steel powders along with local feedstock compounding facilities. In this context, the American Iron and Steel Institute in July 2026 stated that China’s large steel capacity and government subsidies are contributing significantly to global steel overcapacity. It also mentioned that China accounted for nearly half of global steelmaking capacity in 2025, whereas its steel exports increased, thus contributing to the market’s expansion.
The Japan metal injection molding market is gaining enhanced traction owing to strong demand for miniaturization and lightweight components in hybrid and electric vehicles. The domestic manufacturers leverage their deep material science expertise to pioneer specialized feedstock formulations and advanced micro-MIM techniques. The market benefits from highly integrated automation, robotic quality inspection, and sintering technologies that make sure superior surface finishes and tight dimensional tolerances. In addition, the industry thrives on high-value-add component fabrication, tight collaboration with domestic robotics and healthcare OEMs, and an export network that supplies high-performance, net-shape parts to global high-tech industries.
North America Market Insights
The North America market is projected to sustain strategic growth, which is driven mainly by a strong demand for high-performance, specialized components. The regional market is also driven by the advanced healthcare, aerospace, defense, and firearms industries. The market thrives on the domestic production of complex, biocompatible surgical instruments and flight-critical aerospace components. Metal Powder Industries Federation in June 2024 stated that the region’s MIM industry remains fundamentally healthy, with stainless steels, low-alloy steels, and titanium alloys continuing as key materials. Medical and firearms applications remain important, whereas industrial and automotive demand continues to expand, thus making it suitable for standard market growth.
North America Metal Powder Shipments by Material Type: 2022 vs 2023 Market Analysis
|
Type |
2022 Short Tons |
2023 Short Tons |
|
Iron & Steel |
323,311 |
320,234 |
|
Stainless Steel |
7,000 |
6,300 (E) |
|
Copper & Copper Base/Tin |
14,500 |
13,056 |
|
Aluminum |
21,900 |
23,650 |
|
Molybdenum |
766 |
843 |
|
Tungsten |
3,736 |
3,186 |
|
Tungsten Carbide |
5,369 |
4,759 |
|
Nickel |
4,450 |
4,400 |
|
Total |
381,032 |
376,428 |
Source: MPIF
The country’s advanced manufacturing base and strong demand for precision components across automotive, medical devices, electronics, aerospace, and industrial applications are boosting the U.S. metal injection molding market growth. In addition, the presence of established domestic manufacturing capabilities and a broad ecosystem of specialized suppliers also strengthens the market’s development. In January 2024, Sandvik partnered with KBM Advanced Materials in order to distribute Osprey® metal powders for additive manufacturing across the U.S. to improve local availability and reduce delivery times. This agreement will strengthen the U.S. metal powder supply chain, thereby providing faster fulfillment and proper access to materials for AM and MIM applications.
The Canada market is growing at a steady pace of progress which is propelled by aerospace, defense, automotive, and specialized medical device manufacturing sectors. The country’s producers highly focus on fabricating high-durability, complex components that are capable of withstanding extreme environmental conditions, utilizing advanced feedstocks such as titanium and nickel superalloys. The market benefits from strong academic and industrial research partnerships, which foster continuous innovation in cleaner, more sustainable binder formulations and advanced sintering techniques. In addition, the market’s growth is accelerated by the close integration of manufacturers into the North America supply chain.
Europe Market Insights
The Europe market is expected to expand at a considerable rate owing to higher dedication to industrial automation and stringent environmental sustainability standards. In addition, the market depicts a highly integrated regional supply chain, widespread adoption of Industry 4.0 smart factory concepts, and a strong emphasis on fabricating high-value-add, low-volume specialty alloy parts. Market growth is largely driven by the region's premium automotive sector, particularly the transition toward electric and hybrid vehicle components, along with high-end medical device manufacturing. The region’s producers distinguish themselves through sophisticated material science research, pioneering the development of eco-friendly, water-soluble, and catalytic debinding systems.
The country's world-class automotive industry, which requires a massive volume of highly intricate, lightweight components for electric vehicle powertrains, turbochargers, and sensor systems, is the primary factor driving growth in Germany metal injection molding market. The country’s market growth is structurally propelled by a dominant domestic machine-tool infrastructure and deep collaborative research between specialized feedstock compounders and technical universities. Based on the official data published in October 2025, Germany’s automotive industry is a major source of jobs, innovation, exports, and economic growth. The report also states that in order to remain a leading automotive hub, Germany and Europe need to create conditions that allow companies to innovate and compete internationally.
The UK market is growing at a notable pace, which is primarily attributable to the domestic demand for lightweight, high-integrity components used in aircraft engines, military hardware, and surgical equipment. At the same time, manufacturers in this country emphasize material innovation, leveraging strong university-industry research partnerships to pioneer processing techniques for advanced superalloys and biocompatible materials. Based on the government data, which was published in January 2024, the UK has established a USD 57.92 million Defense Materials Centre of Excellence with the main goal of bringing together researchers, universities, and industry to develop advanced materials capable of operating in extreme conditions.
Key Metal Injection Molding Market Players:
- INDO-MIM (India)
- OptiMIM (U.S.)
- Schunk Group (Germany)
- FineMIM (China)
- Dongguan Micro-MIM Manufacturing (China)
- Biomerics (U.S.)
- Dauch Corporation (U.S.)
- Company Overview
- Business Strategy
- Key Product Offerings
- Financial Performance
- Key Performance Indicators
- Risk Analysis
- Recent Development
- Regional Presence
- SWOT Analysis
- INDO-MIM is a leading global MIM manufacturer in this sector, offering integrated design, tooling, materials, finishing, and assembly capabilities. This company primarily serves automotive, aerospace, medical, defense, consumer, and industrial markets, and it has large-scale manufacturing facilities in India, the U.S., and Europe.
- OptiMIM specializes in high-precision MIM components with complex geometries and fine details. Besides, the firm serves automotive, medical, defense, consumer electronics, and industrial applications, and it is supported by broad alloy and customized material capabilities.
- Schunk Group is considered to be a leading MIM manufacturer that specializes in complex, high-precision components. The company’s applications include power electronics, water cooling, automotive, data centers, and wind power.
- FineMIM manufactures precision MIM components that are suitable for consumer electronics, automotive, medical, aerospace, and industrial applications. The firm’s strengths are complex-component manufacturing, precision, and high-volume production.
- Dongguan Micro-MIM Manufacturing is also a prominent player in this sector, which specializes in miniature and complex MIM components, i.e., stainless-steel, titanium, medical, electronics, and industrial parts. The company’s competitive strength lies in customized precision manufacturing as well as high-volume production.
Here is a list of key players operating in the global market:
The leading manufacturers in the global metal injection molding market are intensely contending through production scale, precision, material capabilities, and automation. INDO-MIM and OptiMIM have achieved strong international positions, whereas Schunk has a significant presence in Europe. On the other hand, Asia-based manufacturers, particularly in China, contribute to a highly competitive regional supply base which is supported by growing demand from electronics, automotive, medical, and industrial applications. Competitive differentiation in this sector is structured around complex geometries, high-volume production, tight tolerances, specialized alloys, integrated finishing, and the ability to deliver ready-to-use MIM components.
Corporate Landscape of the Market:
Recent Developments
- In February 2026, Dauch Corporation completed its acquisition of Dowlais Group plc and its subsidiaries, GKN Automotive and GKN Powder Metallurgy, to create a global automotive supplier focused on driveline and metal-forming technologies.
- In October 2024, Biomerics launched a new metal injection molding Center of Excellence to expand its advanced metal manufacturing capabilities for complex medical devices. This technology enables high-volume production of intricate and durable metal components with tight tolerances and complex geometries.
- Report ID: 4916
- Published Date: Aug 25, 2026
- Report Format: PDF, PPT
- Explore a preview of key market trends and insights
- Review sample data tables and segment breakdowns
- Experience the quality of our visual data representations
- Evaluate our report structure and research methodology
- Get a glimpse of competitive landscape analysis
- Understand how regional forecasts are presented
- Assess the depth of company profiling and benchmarking
- Preview how actionable insights can support your strategy
Explore real data and analysis
Frequently Asked Questions (FAQ)
About this Report
Connect with our Expert


Report, 2027-2036



Copyright @ 2026 Research Nester. All Rights Reserved.
