Steel Powder Market Outlook:
Steel Powder Market size was valued at USD 6.2 billion in 2026 and is projected to exceed USD 11.5 billion by the end of 2036, expanding at over 6.4% CAGR during the forecast period, i.e., between 2027-2036. In 2027, the industry size of steel powder is estimated at USD 6.6 billion.
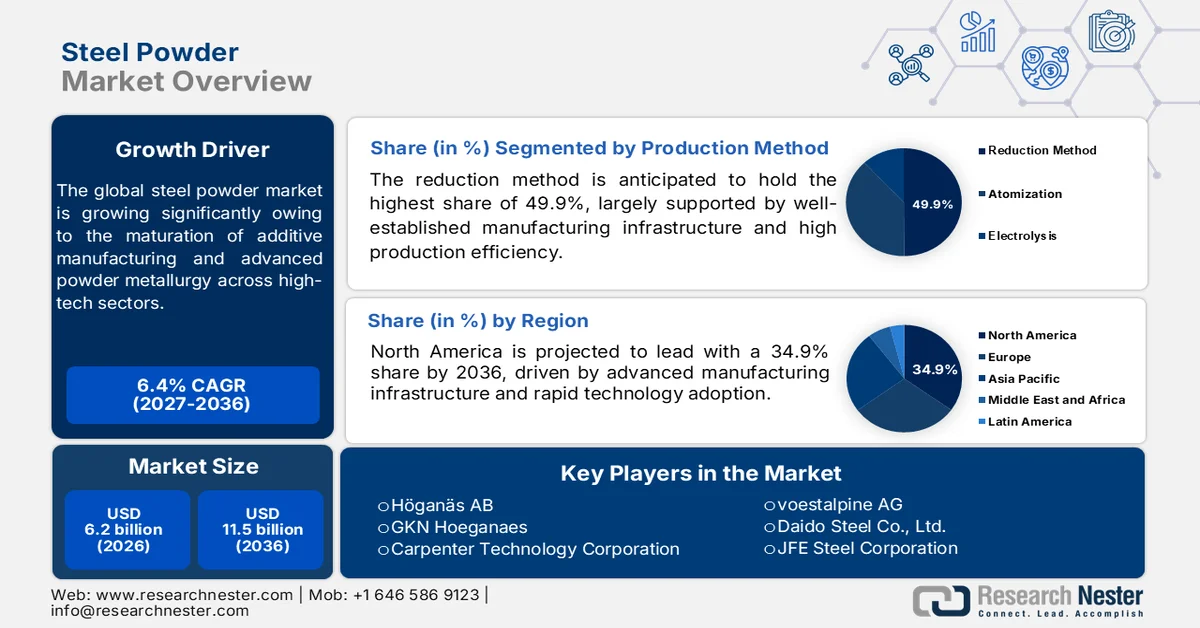
The global steel powder market is entering a transformative growth phase, which is effectively driven by the maturation of additive manufacturing and advanced powder metallurgy across high-tech sectors. In November 2023, the National Institute of Standards and Technology (NIST) stated that additive manufacturing is growing exponentially and enables fast prototyping, material savings, and cost-effective production of customized or small-batch parts. It also mentioned that in the U.S., goods made through additive manufacturing generated about USD 2.8 billion in shipments. The estimated U.S. value added from additive manufacturing is USD 1.4 billion, thus elevating the growth potential of the steel powder industry.
In parallel, the global supply chain in the steel powder market extends from iron ore, scrap, and alloying materials through steelmaking, atomization or other powder-production processes, packaging and delivery to component manufacturers and assembly/production lines. Trade data that covers iron or steel powders and granules represents the well-established international movement of these materials. In this context, the World Integrated Trade Solution stated that in 2024, Japan was the leading exporter of alloy steel powders, with exports worth USD 163.59 million and it was followed by Sweden and the European Union. Canada recorded a significant export quantity of 47.42 million kg, and hence the data shows strong international trade in alloy steel powders, with major exporters across Asia, Europe, and North America.
Alloy Steel Powder Exports by Country: Trade Value and Export Volume, 2024
|
Exporter |
Trade Value (1000 USD) |
Quantity (Kg) |
|
Japan |
163,587.48 |
34,992,300 |
|
Sweden |
116,880.05 |
44,928,500 |
|
European Union |
116,386.65 |
32,955,300 |
|
Canada |
85,456.30 |
47,419,900 |
|
Belgium |
72,281.02 |
6,648,750 |
|
China |
71,202.16 |
25,958,900 |
|
U.S. |
58,698.70 |
16,981,100 |
|
UK |
52,943.10 |
3,321,470 |
|
Korea, Rep. |
32,467.15 |
2,268,890 |
|
Germany |
24,434.18 |
4,014,910 |
Alloy Steel Powder Imports by Country: Trade Value and Import Volume, 2023
|
Importer |
Trade Value (1000 USD) |
Quantity (Kg) |
|
China |
176,018.41 |
51,493,800 |
|
U.S. |
139,189.98 |
55,688,700 |
|
Japan |
122,092.19 |
25,319,100 |
|
European Union |
79,080.38 |
18,052,000 |
|
Germany |
76,621.44 |
12,495,300 |
|
Korea, Rep. |
70,434.10 |
18,615,000 |
|
UK |
31,004.82 |
3,623,280 |
|
Spain |
24,419.33 |
7,818,330 |
|
Philippines |
18,912.86 |
919,297 |
|
Other Asia, nes |
13,510.78 |
1,569,910 |
|
India |
13,436.91 |
3,186,140 |
Source: WITS
Key Steel Powder Market Insights Summary:
Regional Highlights:
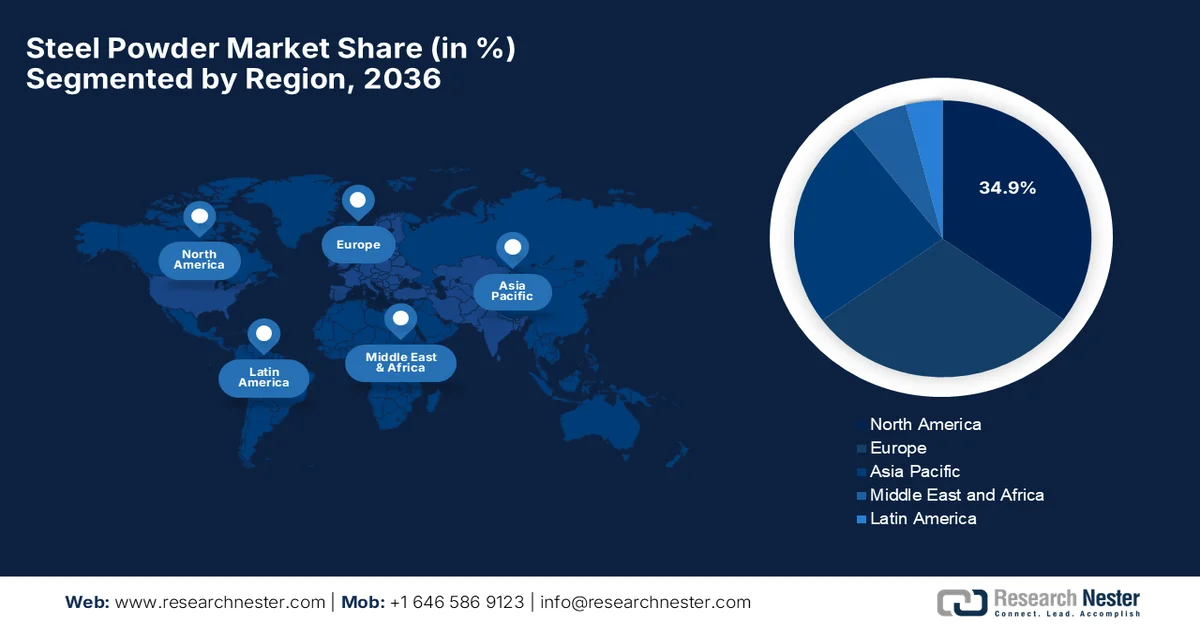
- North America is projected to command a 34.9% share of the steel powder market by 2036, reinforced by advanced manufacturing capabilities, supply chain security initiatives, digital transformation, and the adoption of automated powder processing technologies
- Asia Pacific is expected to register the fastest growth through 2036, propelled by expanding automotive manufacturing, rising EV adoption, and increasing demand for powder metallurgy, metal injection molding, and additive manufacturing technologies
Segment Insights:
- The reduction method is projected to account for a 49.9% share of the steel powder market by 2036, supported by well-established manufacturing infrastructure, high production efficiency, suitable powder characteristics, and advancements in hydrogen-based reduction technologies
- Stainless steel powder is poised for lucrative growth from 2027 to 2036, fueled by increasing adoption in additive manufacturing and the development of customized grades for aerospace, healthcare, and energy applications
Key Growth Trends:
- Technological atomization advances
- Abundant and expanding feedstock
Major Challenges:
- High production and processing costs
- Supply chain volatility for raw materials
Key Players: Höganäs AB, GKN Hoeganaes, Carpenter Technology Corporation, voestalpine AG, Daido Steel Co., Ltd., JFE Steel Corporation, Erasteel, SSAB.
Global Steel Powder Market Forecast and Regional Outlook:
Market Size & Growth Projections:
- 2026 Market Size: USD 6.2 billion
- 2027 Market Size: USD 6.6 billion
- Projected Market Size: USD 11.5 billion by 2036
- Growth Forecasts: 6.4% CAGR (2027-2036)
Key Regional Dynamics:
- Largest Region: North America (34.9% Share by 2036)
- Fastest Growing Region: Asia Pacific
- Dominating Countries: China, United States, Japan, Germany, South Korea
- Emerging Countries: India, Canada, Italy, France, Mexico
Last updated on : 8 September, 2026
Steel Powder Market - Growth Drivers and Challenges
Growth Drivers
- Technological atomization advances: Innovations in terms of gas and water atomization techniques and recycled processes are significantly improving steel powder quality. Modern processing propels superior particle sphericity, consistent sizing, and higher chemical purity. These technical enhancements improve powder flowability and melting consistency, thus propelling extensive growth in the steel powder market. In March 2024, SSAB launched SSAB AM Tough Zero®, which is described as the world’s first emission-free steel powder for commercial delivery, made from recycled SSAB Zero® steel. This powder is produced using fossil-free energy, which enables 3D-printed steel components with virtually zero emissions from the steelmaking process, thus making it suitable for standard market growth.
- Abundant and expanding feedstock: The massive global surplus of steel creates a proper supply of primary steel and industrial scrap metal. Therefore, this brings down raw material input costs for powder manufacturers, who use this scrap as the main feedstock for atomization plants, thereby driving extensive business in the steel powder market. In this context, the Organization for Economic Co-operation and Development (OECD) in June 2026 stated that global steelmaking capacity reached a substantial 2,445 Mt in 2025, whereas excess capacity increased to 640 Mt, reflecting growing oversupply. The article also mentions that excess capacity is projected to reach 745 Mt by 2028. India was a major contributor to capacity growth, which added 41.4 Mt (+28.8%) between 2021 and 2025.
Global Steelmaking Capacity by Region, 2021-2025
|
Region |
2021 |
2022 |
2023 |
2024 |
2025 |
2021 vs 2025 (volume) |
2021 vs 2025 (%) |
|
Africa |
43.5 |
47.1 |
48.1 |
48.5 |
49.4 |
6 |
13.7% |
|
Asia |
1 632.7 |
1 646.2 |
1 643.0 |
1 660.6 |
1 658.6 |
25.9 |
1.6% |
|
China (People’s Republic of) |
1 146.5 |
1 149.9 |
1 141.5 |
1 141.5 |
1 135.5 |
-11 |
-1.0% |
|
India |
143.9 |
154 |
161.2 |
179.5 |
185.3 |
41.4 |
28.8% |
|
Japan |
122.4 |
122.4 |
117.8 |
117 |
113.6 |
-8.8 |
-7.2% |
|
ASEAN |
80.4 |
80.4 |
82.9 |
82.9 |
86 |
5.5 |
6.9% |
|
Viet Nam |
26 |
26 |
26 |
26 |
29 |
3 |
11.6% |
|
CIS + Ukraine |
130.6 |
114.3 |
114.3 |
114.3 |
114.5 |
-16.1 |
-12.3% |
|
Europe |
280.3 |
281.5 |
283.7 |
280.5 |
280.5 |
0.2 |
0.1% |
|
European Union |
205.6 |
205.6 |
205.7 |
205.7 |
204.7 |
-0.9 |
-0.4% |
|
Other Europe |
74.7 |
75.9 |
78.1 |
74.9 |
75.8 |
1.1 |
1.5% |
|
Latin America |
73.9 |
73.9 |
74.2 |
74.2 |
74.4 |
0.5 |
0.6% |
|
Middle East |
89 |
92.3 |
93.9 |
94.9 |
96.2 |
7.2 |
8.1% |
|
Iran |
54.8 |
57.4 |
58.2 |
59.2 |
60 |
5.2 |
9.4% |
|
North America |
157.7 |
162.8 |
163.3 |
163.3 |
165.2 |
7.4 |
4.7% |
|
Oceania |
6.4 |
6.4 |
6.4 |
6.4 |
6.4 |
0 |
0.0% |
|
OECD Member countries |
640 |
646.3 |
644.4 |
640.4 |
637.2 |
-2.8 |
-0.4% |
|
OECD partner economies |
1 774 |
1 778.1 |
1 782.4 |
1 802.2 |
1 807.9 |
33.9 |
1.9% |
|
World total |
2 414 |
2 424.3 |
2 426.8 |
2 442.6 |
2 445.1 |
|
|
Challenges
- High production and processing costs: The production of high-quality steel powder needs manufacturing techniques such as gas or water atomization. These methods require immense energy inputs and highly specialized equipment, which leads to high capital expenditure. Therefore, maintaining precise particle size distribution and chemical purity adds substantial operational costs. For most of the mid-sized manufacturers, these substantial initial and ongoing expenses restrict market entry. In addition, the existence of post-processing steps, i.e., thermal treatment and classification, inflates final product prices. This cost disparity dampens widespread adoption, thus causing restrictions to steel powder market expansion.
- Supply chain volatility for raw materials: The steel powder market is extremely vulnerable to fluctuations in the availability and price of scrap metal and alloying elements. Additives such as nickel, chromium, and molybdenum witness more frequent price swings, driven by geopolitical tensions and certain trade policies. Steel powder production depends on a stable feed of specific alloy inputs, due to which any type of disruption creates immediate bottlenecks. Apart from this, energy grid instability and rising electricity tariffs directly impact the cost-heavy atomization plants. Therefore, manufacturers find it difficult to maintain stable pricing structures due to these unpredictable upstream variables. Hence, this supply chain fragility forces companies to carry expensive safety stocks or risk production shutdowns, ultimately skewing profit margins.
Steel Powder Market Size and Forecast:
| Report Attribute | Details |
|---|---|
|
Base Year |
2026 |
|
Forecast Period |
2027-2036 |
|
CAGR |
6.4% |
|
Base Year Market Size (2026) |
USD 6.2 billion |
|
Forecast Year Market Size (2036) |
USD 11.5 billion |
|
Regional Scope |
|
Steel Powder Market Segmentation:
Production Method Segment Analysis
The reduction method is anticipated to hold the highest share of 49.9% in the production method category during the discussed timeframe. This dominating position in the steel powder market is largely supported by well-established manufacturing infrastructure, high production efficiency, and the ability to produce powders with suitable compressibility and sintering characteristics. In addition, ongoing advancements in hydrogen-based reduction technologies enhance the method's environmental profile, thereby solidifying its relevance in sustainable steel powder production. In July 2024, researchers at the Oak Ridge National Laboratory demonstrated that hematite powder can be reduced 10 times faster using an argon- hydrogen plasma process with 2% hydrogen. This faster reduction could enable direct ore-to-part manufacturing through blown-powder directed energy deposition, thereby reducing the need for conventional processing steps.
Type Segment Analysis
In terms of type, the stainless steel powder sub-segment is anticipated to grow with a lucrative share in the steel powder market from 2027 to 2036. The growth of stainless steel can be attributed to the expanding adoption of specialized grades in additive manufacturing, particularly for complex components requiring application-specific material properties. Increasing development of customized stainless steel powder grades for aerospace, healthcare, energy, and expansion of production is rising opportunities for manufacturers to expand their stainless-steel powder portfolios. In May 2025, Outokumpu announced the expansion of its stainless-steel metal powder production, delivering its first batch of a new grade for aerospace and aviation 3D-printing applications.
Application Segment Analysis
The automotive industry, which is a part of the application segment, is forecasted to capture a noteworthy share in the steel powder market during the assessed timeframe. The expanding integration of powder metallurgy into both conventional and electrified vehicle platforms is the primary fueling factor behind this leadership. The transition toward electric and hybrid vehicles is creating opportunities for powder-based gears, drivetrain components, electric-motor components, inductors, and other compact parts. Apart from this, manufacturers across different nations are looking for material-efficient production routes for high-volume components, thus denoting a wider segment scope. Furthermore, the growing emphasis on component miniaturization and design optimization is encouraging automakers to adopt powder-based manufacturing.
Our in-depth analysis of the steel powder market includes the following segments:
|
Segment |
Subsegments |
|
Production Method |
|
|
Type |
|
|
Application |
|
|
Particle Size |
|

Vishnu Nair
Head - Global Business DevelopmentCustomize this report to your requirements — connect with our consultant for personalized insights and options.
Steel Powder Market - Regional Analysis
North America Market Insights
North America steel powder market is anticipated to hold the highest share of 34.9% during the discussed timeframe. The region’s leadership in this sector is primarily propelled by an advanced manufacturing ecosystem and the rapid integration of breakthrough technologies. This momentum is also amplified by an emphasis on supply chain security and digital transformation, which encourages manufacturers to adopt automated powder handling systems and domestic near-net-shape processing. In December 2024, Continuum Powders announced the inauguration of its new global headquarters and sustainable metal powder manufacturing facility in Houston, Texas, which is described as North America’s largest sustainable metal powder production site. This facility uses the proprietary Greyhound M2P plasma atomization process to convert alloyed metal waste into high-quality powder in a single step, thus reducing transportation, processing, and raw-material requirements.
The exponential growth of the domestic aerospace, space exploration, and defense sectors drives surging growth in the U.S. steel powder market. These sectors utilize high-grade steel powders for specialized on-demand 3D printing and complex component fabrication. A federal emphasis on re-shoring critical manufacturing infrastructure and securing domestic supply chains with extensive raw material capabilities is driving capital investments into local atomization facilities and powder metallurgy innovation. In this context, the U.S. Geological Survey (USGS) disclosed that the country produced 82 million metric tons of raw steel in 2025, with a sales value of USD 149 billion. Raw steel production capacity was 105 million metric tons per year, whereas steel mill product shipments reached 82 million metric tons, thus indicating a positive steel powder market opportunity.
U.S. Iron and Steel Market Statistics: Production, Imports, Exports and Consumption in metric tons, 2021 - 2025
|
Indicator |
2021 |
2022 |
2023 |
2024 |
2025 |
|
Pig iron production |
22.2 |
20.0 |
22.5 |
20.6 |
21 |
|
Raw steel production |
85.8 |
80.5 |
81.4 |
79.5 |
82 |
|
Shipments, steel mill products |
85.9 |
81.2 |
81.0 |
78.7 |
82 |
|
Finished steel imports |
20.6 |
22.9 |
19.7 |
20.4 |
19 |
|
Semifinished steel imports |
7.9 |
5.1 |
5.9 |
5.8 |
5 |
|
Total steel imports |
28.5 |
28.0 |
25.6 |
26.2 |
24 |
|
Finished steel exports |
7.4 |
7.5 |
7.9 |
7.9 |
6 |
|
Semifinished steel exports |
0.1 |
0.1 |
0.3 |
0.1 |
0.1 |
|
Total steel exports |
7.5 |
7.6 |
8.2 |
8.0 |
7 |
|
Apparent consumption |
100 |
96.2 |
92.4 |
91.1 |
95 |
|
Net import reliance (%) |
14 |
16 |
12 |
14 |
13 |
Source: USGS
The Canada steel powder market is projected for immense growth, which is driven by the nation's robust natural resource sector and strong focus on industrial sustainability. Growth is largely supported by the country’s well-established automotive manufacturing corridor, which is rapidly pivoting toward electric vehicle supply chains and demanding powder metallurgy components for advanced drivetrains. In addition, the country's prominent mining, heavy machinery, and aerospace industries increasingly adopt steel powder technologies for on-demand component fabrication, maintenance, and complex tooling applications. This growth momentum is also catalyzed by a strong focus on domestic research and development, particularly in developing high-purity alloy formulations.
APAC Market Insights
The Asia Pacific steel powder market is expected to grow at the fastest rate during the forecast period. The region’s leadership is majorly propelled by automotive manufacturing hubs, where a swift transition toward electric vehicles is driving adoption of high-performance powder metallurgy for complex transmission parts. In addition, booming electronics, industrial robotics, and heavy machinery sectors across major developing economies are creating sustained demand for metal injection moulding and automated additive manufacturing technologies. The steel powder market is supported by rapid infrastructure development and a continuous influx of foreign direct investment, which allows local manufacturers to upgrade to advanced gas and water atomization systems.
The country's position as a predominant hub for global electric vehicle and battery supply chains creates surging demand in the China steel powder market. The country’s consumer electronics and domestic robotics sectors are utilizing ultra-fine steel powders for high-precision metal injection moulding applications. Strategic national industrial policies and substantial state-backed capital investments are also accelerating the raw material supply. Based on government data which was published in December 2024, China launched a three-year action plan in order to upgrade its raw materials industries, including steel, by improving high-end supply, digitalization, green development, and industry safety. It also mentions that by 2027, this particular plan targets more than 200 digital transformation standards, more than 100 new-material standards, and over 100 green and low-carbon standards.
In India, the steel powder market is witnessing noteworthy growth, which is primarily propelled by rising industrialization, expanding infrastructure, and the scaling of its domestic manufacturing sector under supportive government initiatives. A primary catalyst for the country’s market is the development of India's aerospace, defense, and localized electronics manufacturing ecosystems, which is driving a steady shift toward additive manufacturing. In May 2026, India Brand Equity Foundation disclosed that the country’s defense manufacturing sector is expanding rapidly, supported by government initiatives, rising domestic production, and growing exports. It also mentioned some key growth areas, i.e., aerospace, missiles, naval systems, drones, electronics, and advanced defense technologies, thus propelling demand for steel powders.
Europe Market Insights
The Europe steel powder market is predicted to grow at a considerable rate from 2027 to 2036. The region’s growth in this sector is mainly propelled by the presence of leading market players and their strategic activities. This momentum is also accelerated by stringent regional carbon-reduction mandates, which compel manufacturers to champion near-net-shape processing techniques that drastically reduce raw material waste. In November 2023, ArcelorMittal entered the additive manufacturing industry by supplying high-quality steel powders from its new Spain facility. The company will produce powders from recycled steel by using renewable energy, mainly targeting applications across automotive, aerospace, medical, and energy sectors.
The structural transformation of its world-class luxury automotive industry, wherein manufacturers are deploying advanced metal injection moulding to mass-produce intricate components for electric mobility, is the main driving factor for the steel powder market in Germany. In addition, the integration of Industry 4.0 automation and smart factory systems across the country’s vast machine tool and industrial robotics sectors drives continuous demand for specialized, high-wear steel powder alloys. In March 2023, Outokumpu entered the metal powder sector for additive manufacturing with a new atomization plant in Krefeld, Germany. This facility uses locally generated steel scrap to produce powders for AM, metal injection moulding, binder jetting, and HIP applications, thus positively benefiting the market’s growth.
The UK steel powder market is gaining enhanced traction, which is structured around high-value engineering, advanced research, and structural supply chain re-shoring. Market growth is fundamentally propelled by the nation’s expanding aerospace and satellite manufacturing clusters, which heavily utilize ultra-pure steel powders to 3D print complex, lightweight structural components for next-generation aviation. In November 2025, Renishaw joined the USD 51.45 million DECSAM programme, which was led by Airbus, to advance sustainable aerospace additive manufacturing in the UK. This project focuses on improving laser powder bed fusion through better process control, productivity, automation, and powder sustainability, hence denoting an optimistic market opportunity.
Key Steel Powder Market Players:
- Höganäs AB (Sweden)
- GKN Hoeganaes (U.S.)
- Carpenter Technology Corporation (U.S.)
- voestalpine AG (Austria)
- Daido Steel Co., Ltd. (Japan)
- JFE Steel Corporation (Japan)
- Erasteel (France)
- SSAB (Sweden)
- Company Overview
- Business Strategy
- Key Product Offerings
- Financial Performance
- Key Performance Indicators
- Risk Analysis
- Recent Development
- Regional Presence
- SWOT Analysis
- Höganäs AB offers a broad portfolio of stainless steel powders which are suitable for pressing, sintering, and other powder metallurgy applications. The company’s range includes austenitic grades such as 304L and 316L, along with ferritic and ferritic/martensitic grades for automotive, industrial, and precision components.
- GKN Hoeganaes produces steel and metal powders for powder metallurgy, forged PM, and additive manufacturing. Besides, the firm’s competitive strength arises from broad alloy capabilities, advanced atomization, powder testing, and application-focused material solutions.
- Carpenter Technology Corporation is a prominent player in this sector that supplies specialized metal powders for additive manufacturing. Its PowderRange® 316L stainless steel powder provides corrosion resistance, toughness, and weldability for different applications.
- voestalpine AG offers iron-based powders for additive manufacturing, which include corrosion-resistant, maraging, precipitation-hardening, and hot-work tool steels. The firm’s portfolio primarily targets applications in toolmaking, automotive, aerospace, and medical industries.
- Daido Steel Co., Ltd. is a central player in this sector that manufactures stainless steel, high-alloy, MIM, and additive manufacturing powders. The company’s stainless steel portfolio consists of grades such as DAP304L, DAP316L, DAP410L, DAP430L, and DAP444L.
Here is a list of key players operating in the global steel powder market:
The global steel powder market depicts a mix of different powder-metallurgy producers along with a few specialty steel manufacturers that are intensely competing on alloy composition, purity, and application-specific performance. Leading manufacturers in this sector maintain portfolios serving conventional powder metallurgy, metal injection molding, and additive manufacturing, whereas regional and specialized players differentiate through high-performance tool steels, stainless steel powders, and customized alloy solutions. In August 2025, Sandvik launched Osprey® MAR 55, which is a high-strength tool steel powder combining excellent weldability, toughness, and wear resistance. This is especially designed for PBF-LB additive manufacturing, and it can achieve hardness above 50 HRC without plate preheating or cryogenic treatment.
Corporate Landscape of the Steel Powder Market:
Recent Developments
- In June 2026, SSAB expanded its Oxelösund, Sweden facility to scale up high-performance steel powder production for additive manufacturing. This upgraded plant will ramp up production with an annual capacity of around 350 tons.
- In February 2025, Erasteel acquired selected assets of U.S.-based Crucible Industries, expanding its presence in the U.S. steel market. The deal strengthens Erasteel’s position in powder-metallurgy high-speed steels and stainless steels.
- Report ID: 5756
- Published Date: Sep 08, 2026
- Report Format: PDF, PPT
- Explore a preview of key market trends and insights
- Review sample data tables and segment breakdowns
- Experience the quality of our visual data representations
- Evaluate our report structure and research methodology
- Get a glimpse of competitive landscape analysis
- Understand how regional forecasts are presented
- Assess the depth of company profiling and benchmarking
- Preview how actionable insights can support your strategy
Explore real data and analysis
Frequently Asked Questions (FAQ)
About this Report
Connect with our Expert


Report, 2027-2036



Copyright @ 2026 Research Nester. All Rights Reserved.
