Plasma Fractionation Market Outlook:
Plasma Fractionation Market size was valued at USD 40.6 billion in 2025 and is projected to cross USD 101.5 billion by the end of 2035, expanding at more than 9.6% CAGR during the forecast period, i.e., 2026-2035. In 2026, the industry size of plasma fractionation is estimated at USD 44.5 billion.
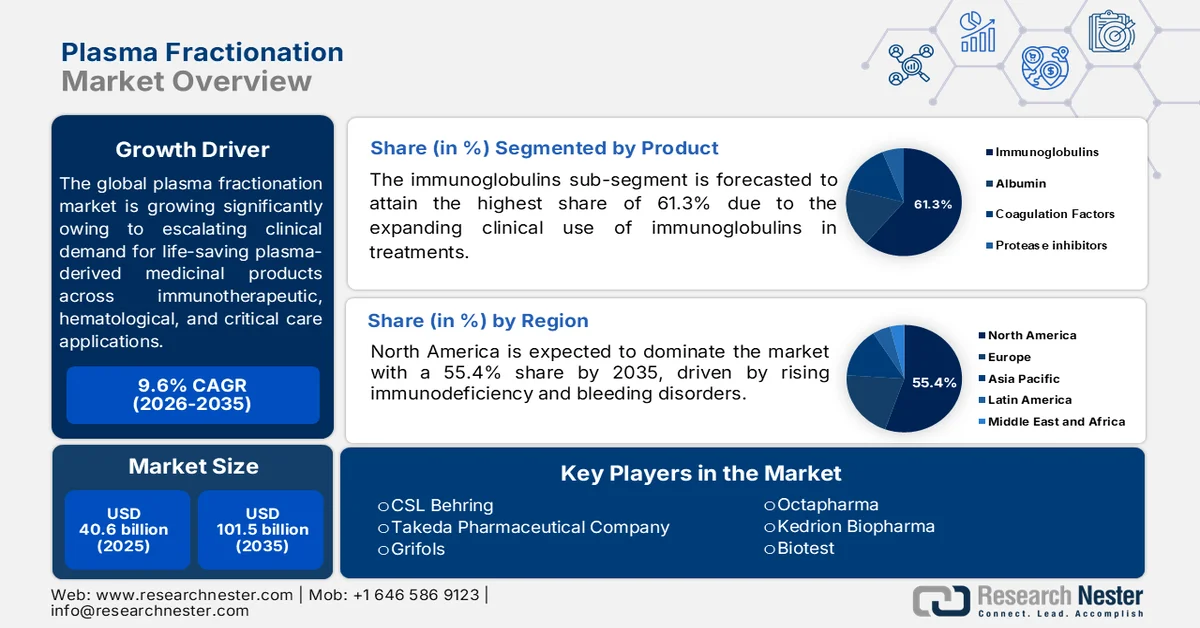
The global plasma fractionation market is projected to experience steady expansion, which is driven by the escalating clinical demand for plasma-derived medicinal products across immunotherapeutic, hematological, and critical care applications. Progress in automated fractionation technologies, along with the expansion of plasma collection infrastructure in emerging economies, is also boosting manufacturing capacities. According to an article published by the World Health Organization in June 2026, around 120.4 million blood donations are collected worldwide, with high-income countries having much higher donation rates than low-income countries. It also mentioned that only 49 of 168 reporting countries produce plasma-derived medicinal products from locally collected plasma, underscoring the urgent need for stronger national blood systems and increased plasma collection and fractionation capacity.
Furthermore, the rising global prevalence of autoimmune disorders, immunodeficiencies, and rare bleeding conditions ensures a sustained and expanding patient base in the market globally. In May 2024, the Centers for Disease Control and Prevention stated that Hemophilia affects up to 33,000 males in the U.S., with hemophilia A occurring about three to four times more often than hemophilia B, and more than 40% of affected males having severe disease. The article also mentioned that approximately 20% of people with hemophilia A and 3% with hemophilia B may develop inhibitors against clotting-factor treatments, thus expanding demand in the market.
Key Plasma Fractionation Market Insights Summary:
Regional Highlights:
- North America is projected to secure the leading 55.4% share of the plasma fractionation market by 2035, underpinned by rising clinical adoption of immunoglobulins, a growing burden of immunodeficiency and chronic diseases, and well-established healthcare infrastructure
- Asia Pacific is positioned for notable expansion through 2035, supported by its large patient population, increasing awareness of rare genetic disorders, rising healthcare expenditure, and initiatives to strengthen domestic plasma collection
Segment Insights:
- The immunoglobulins sub-segment is anticipated to command the largest 61.3% share of the plasma fractionation market by 2035, driven by the increasing prevalence of immunodeficiency disorders, expanding clinical applications, and rising demand for replacement and immunomodulatory therapies
- The neurology sub-segment is expected to capture a lucrative share by 2035, fueled by greater adoption of plasma-derived immunoglobulin therapies for neurological disorders, expanding neuroimmunology indications, and increasing demand for effective immunomodulatory treatments
Key Growth Trends:
- Technological advancements in fractionation
- Infrastructure expansion in emerging economies
Major Challenges:
- Limited plasma supply
- Risk of contamination and product safety
Key Players: CSL Behring (Australia) ,Takeda Pharmaceutical Company (Japan) ,Grifols (Spain) ,Octapharma (Switzerland) ,Kedrion Biopharma (Italy) ,Biotest (Germany) ,ADMA Biologics (U.S.).
Global Plasma Fractionation Market Forecast and Regional Outlook:
Market Size & Growth Projections:
- 2025 Market Size: USD 40.6 billion
- 2026 Market Size: USD 44.5 billion
- Projected Market Size: USD 101.5 billion by 2035
- Growth Forecasts: 9.6% CAGR (2026-2035)
Key Regional Dynamics:
- Largest Region: North America (55.4% share by 2035)
- Fastest Growing Region: Asia Pacific
- Dominating Countries: United States, Germany, China, Japan, France
- Emerging Countries: China, India, Japan, South Korea, Thailand
Last updated on : 25 August, 2026
Plasma Fractionation Market - Growth Drivers and Challenges
Growth Drivers
- Technological advancements in fractionation: Continued innovations in terms of purification techniques and automated yield optimization readily propel the plasma fractionation market forward. Modern chromatography and filtration processes allow manufacturers to extract higher volumes of therapeutic proteins from every liter of plasma. In March 2026, CSL announced an investment of USD 1.5 billion to expand its Kankakee, Illinois, facility, increasing its capacity to manufacture plasma-derived medicines and respond to the growing needs of patients with rare and immune-related diseases. The expansion will introduce Horizon 2 technology, which is especially designed to improve plasma-processing efficiency and increase the amount of immunoglobulin produced from the same quantity of donated plasma.
- Infrastructure expansion in emerging economies: Healthcare modernization across developing regions effectively accelerates momentum in the market globally. Governments in both developed and developing nations are actively making investments in terms of local plasma collection networks and building specialized fractionation facilities. In December 2023, Indonesia began construction of its first plasma fractionation facility in Cikarang, West Java, which is through a partnership involving the Ministry of Health, the Indonesia Red Cross, and private-sector organizations. Besides, this particular project aims to reduce the country’s dependence on imported plasma-derived medicines, improve access to affordable treatments, and make better use of locally collected plasma.
Challenges
- Limited plasma supply: A major challenge for the market is the limited availability of high-quality human plasma, which is required to manufacture plasma-derived therapies. Plasma collection depends on voluntary donors, which makes supply vulnerable to fluctuations in donation rates, public health emergencies, as well as changes in donor eligibility requirements. In addition, rising demand for immunoglobulins and other plasma-derived products is putting additional pressure on available plasma supplies. Establishing and operating plasma collection centers also requires significant investment, regulatory compliance, trained personnel, and donor recruitment programs, thus causing obstacles to the growth of the global market.
- Risk of contamination and product safety: Ensuring the safety of plasma-derived products is yet another major challenge as the starting material is collected from human donors. Although manufacturers in the market employ extensive donor screening, infectious-disease testing, purification, filtration, and virus inactivation technologies, the risk of contamination needs to be carefully controlled throughout production. In this context, manufacturers need quality-management systems and multiple safety barriers in order to minimize the possibility of transmitting viruses or other pathogens. Any type of contamination or product-quality issue can result in recalls, regulatory action, and financial losses. Furthermore, maintaining consistent quality across large volumes of plasma collected from different donors can be technically demanding.
Plasma Fractionation Market Size and Forecast:
| Report Attribute | Details |
|---|---|
|
Base Year |
2025 |
|
Forecast Period |
2026-2035 |
|
CAGR |
9.6% |
|
Base Year Market Size (2025) |
USD 40.6 billion |
|
Forecast Year Market Size (2035) |
USD 101.5 billion |
|
Regional Scope |
|
Plasma Fractionation Market Segmentation:
Product Segment Analysis
On the basis of product, the immunoglobulins sub-segment is forecasted to attain the highest share of 61.3% during the assessed timeframe. Its growth in the plasma fractionation market is largely attributable to the increasing prevalence of primary and secondary immunodeficiency disorders, along with the expanding clinical use of immunoglobulins in treatment. In addition, the rising demand for immunoglobulin replacement and immunomodulatory therapies, coupled with improvements in plasma collection and fractionation capacity, is supporting segment growth. In this context, Takeda in December 2024 announced the approval of HYQVIA 10% S.C. Injection Set in Japan for patients with agammaglobulinemia or hypogammaglobulinemia. This is the country’s first facilitated subcutaneous immunoglobulin therapy for these conditions.
Application Segment Analysis
By the end of 2035, neurology is anticipated to grow, holding a lucrative share in the market. The segment’s growth in this sector is effectively propelled by the increasing adoption of plasma-derived immunoglobulin therapies for neurological disorders. This adoption is particularly witnessed for chronic inflammatory demyelinating polyneuropathy, along with the expansion of approved indications and treatment options for neuroimmunology conditions. Additionally, the rising disease burden of neurological disorders and growing demand for effective immunomodulatory therapies are supporting segment expansion. Apart from this, increasing healthcare expenditure, improved diagnosis of neuroimmunology conditions, and greater access to advanced plasma-derived therapies are contributing to market growth.
Method Segment Analysis
The chromatography sub-segment, which is a part of the method segment, is expected to grow with a noteworthy share in the market from 2026 to 2035. Its high separation efficiency, ability to achieve greater product purity, and increasing application in the purification of plasma-derived proteins drive the sub-segment’s growth. The growing demand for high-quality immunoglobulins, albumin, and other therapeutic plasma proteins is encouraging manufacturers to opt for chromatographic techniques for improved downstream processing. As of May 2026, data from the U.S. Food and Drug Administration (FDA) show that GAMUNEX-C is a 10% human immune globulin product manufactured by Grifols Biologicals LLC. This product is purified by using caprylate/chromatography technology and is administered to provide immunoglobulin replacement or immune-modulating effects depending on the condition being treated.
Our in-depth analysis of the plasma fractionation includes the following segments:
|
Segment |
Subsegments |
|
Product |
|
|
Application |
|
|
Method |
|
|
End use |
|

Vishnu Nair
Head - Global Business DevelopmentCustomize this report to your requirements — connect with our consultant for personalized insights and options.
Plasma Fractionation Market - Regional Analysis
North America Market Insights
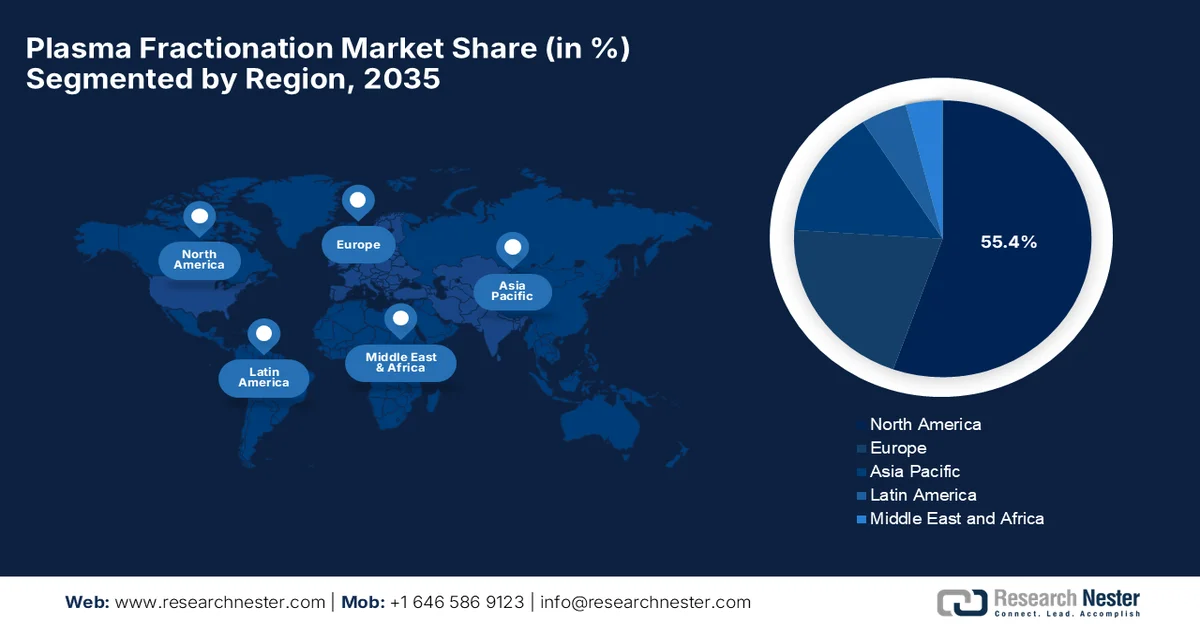
North America plasma fractionation market is anticipated to garner the highest share of 55.4% during the discussed timeframe. The region’s upliftment in this sector is largely propelled by the rising prevalence of immunodeficiency disorders, bleeding conditions, and chronic diseases that necessitate therapies derived from blood plasma. This expansion is also fueled by an aging population, increasing clinical adoption of immunoglobulins, and a well-established healthcare infrastructure with a high awareness of advanced biologic treatments. In October 2025, Grifols announced the U.S. launch of Yimmugo®, which is a 10% intravenous immunoglobulin (IVIg) developed by Biotest and approved by the FDA in 2024 for treating primary humoral immunodeficiency in patients aged 2 years and older.
High and growing clinical demand for plasma-derived therapies, especially immunoglobulins and coagulation factors are important factor driving the U.S. plasma fractionation market. The market benefits significantly from the country's status as the predominant hub for source plasma collection and is supported by an infrastructure of commercial donation centers and fractionation facilities. In this context, ADMA Biologics in July 2023 received FDA approval for its ninth plasma collection center in Dallas, Georgia, to expand its capacity to collect human source plasma for the manufacture of plasma-derived therapies. This facility began collecting plasma in 2022 and uses advanced collection technology and automated registration, thus making it suitable for standard market growth.
The Canada market has a strong opportunity to grow in the upcoming years owing to a strategic shift toward long-term domestic security contracts. The country’s health authorities partner with global biopharmaceutical leaders to fractionate Canada-sourced plasma and guarantee a stable supply of finished therapies. This transition is also effectively supported by ongoing provincial initiatives to expand local plasma collection networks and reduce historical dependencies on imports. In addition, a rigorous regulatory environment overseen by Health Canada ensures high safety standards, whereas public funding models facilitate equitable patient access to these essential biologic medications, thus contributing to the market’s expansion.
APAC Market Insights
The Asia Pacific market is expanding at a notable rate, which is fueled by a massive patient population, rising awareness of rare genetic disorders, and increasing healthcare expenditures across emerging economies. Market growth is also driven by government initiatives that aim to reduce dependency on imported blood products by establishing domestic fractionation facilities and encouraging local plasma donation. In July 2026, Takeda and the government of Indonesia launched a multi-year collaboration to strengthen Indonesia’s plasma ecosystem, expand access to plasma-derived medicinal products, and enhance national healthcare resilience. Takeda will initially invest up to USD 30 million over a span of two years to pilot plasma donation centers, thus positively benefiting the market’s expansion.
The existence of stringent government policies which are aimed at achieving national self-sufficiency in blood products is powering the China plasma fractionation market. The rapid consolidation among state-backed and leading domestic biopharmaceutical companies, along with the strict regulation and expansion of local plasmapheresis stations, is positioning the market for extensive growth. Based on the government data published in June 2024, China’s National Medical Products Administration introduced a three-year action plan in order to accelerate digital and intelligent transformation across blood product manufacturing, to strengthen quality, safety, and regulatory oversight. This plan covers digital management of plasma receipt, blood product production and testing, as well as information-system compliance and security, thus contributing to market expansion.
The Japan plasma fractionation market is growing exponentially owing to the presence of an aging population and an increasing clinical requirement for plasma-derived therapies to treat disorders. The country’s market operates under a strict government-led philosophy of self-sufficiency, which prioritizes the utilization of domestic blood donations for the manufacturing of essential therapeutics such as immunoglobulins and albumin. Based on the government data published in November 2024, Japan’s Pharmaceutical Affairs Council reviewed the FY2025 blood donation and supply-demand plans, and it targets 2,240,000 liters of donated blood to support transfusion needs and domestic plasma-derived product manufacturing. The meeting also underscored growing demand for human immunoglobulin and the need to strengthen domestic fractionation capacity, and it is using imports to maintain short-term supply stability.
Europe Market Insights
The Europe market is projected to expand at a considerable rate as it possesses a mix of public, non-profit, and private plasma collection systems. Several countries in this region are moving toward legislative frameworks that support co-existence models to increase plasma collection volumes. Market growth is further propelled by advanced technological integration in manufacturing facilities and high clinical utilization guidelines for immunoglobulins. In June 2026, Grifols began construction of a new plasma-derived medicines manufacturing facility in Lliçà de Vall, Barcelona, with an initial investment of USD 184.3 million. This facility will increase Grifols’ Europe plasma fractionation capacity by three million liters annually, thus strengthening the region’s supply of immunoglobulins and other plasma-derived therapies.
The continuous investments from leading biopharmaceutical companies in expanding domestic manufacturing capacities and implementing viral safety and purification technologies are responsibly boosting the market in Germany. A highly organized healthcare infrastructure, efficient distribution networks, and robust reimbursement policies under the statutory health insurance system drive consistent growth of the country’s market. In this context, CSL in March 2023 opened a new USD 470 million plasma fractionation facility in Marburg, Germany, after five years of construction, thereby expanding its capacity to convert donated human plasma into essential medicines. This new CSL Behring facility uses advanced technology, automation, and optimized processes to quadruple the site’s existing plasma fractionation capacity.
The UK plasma fractionation market is growing at a rapid pace owing to an increasing clinical need for immunoglobulins and specific coagulation factors in order to treat primary immunodeficiencies and rare neurological conditions. Besides, this expansion is also supported by long-term strategic partnerships between the UK government and global biopharmaceutical leaders to fractionate UK-sourced plasma into finished therapies. Based on government data, which was published in August 2023, NHS England awarded a total of USD 814 million contract to Octapharma AG for the domestic fractionation of UK plasma and the supply of plasma-derived products, including albumin and immunoglobulins. In addition, this five-year supply contract runs from January 2025 through December 2029, supporting the NHS’s access to essential plasma-derived medicines from a UK-focused supply arrangement.
Key Plasma Fractionation Market Players:
- CSL Behring (Australia)
- Takeda Pharmaceutical Company (Japan)
- Grifols (Spain)
- Octapharma (Switzerland)
- Kedrion Biopharma (Italy)
- Biotest (Germany)
- ADMA Biologics (U.S.)
- Company Overview
- Business Strategy
- Key Product Offerings
- Financial Performance
- Key Performance Indicators
- Risk Analysis
- Recent Development
- Regional Presence
- SWOT Analysis
- CSL Behring is a leading manufacturer of plasma-derived therapies that uses plasma fractionation as a core technology. The company’s integrated operations are structured around plasma collection, fractionation, purification, and finished-product manufacturing.
- Grifols is a central player in this sector and is a major plasma-derived medicines manufacturer with extensive fractionation and purification capabilities. Its portfolio includes immunoglobulins, albumin, and coagulation therapies.
- Octapharma manufactures plasma-derived and recombinant therapeutic proteins, with key products being immunoglobulins, albumin, and coagulation therapies. The firm’s integrated production process covers plasma fractionation, purification, virus safety, filling, and quality control.
- Takeda Pharmaceutical Company is yet another major manufacturer of plasma-derived therapies, which consists of an integrated business spanning plasma collection, fractionation, purification, and finished-product manufacturing.
- Kedrion Biopharma specializes in terms of plasma-derived therapeutic products, i.e., immunoglobulins, albumin, and coagulation factors. In addition, the company’s integrated manufacturing network and research into underutilized plasma fractions support its strong position in the global market.
Here is a list of key players operating in the global market:
The global plasma fractionation market is relatively consolidated, and it hosts a small group of large manufacturers holding broad geographic coverage and extensive portfolios, i.e., immunoglobulins, albumin, coagulation factors, and other plasma-derived therapies. CSL Behring, Takeda, Grifols, and Octapharma are among the leading global participants, which are effectively supported by integrated plasma collection, fractionation, purification, and finished-product manufacturing capabilities. Competition in this sector is structured around plasma availability, manufacturing capacity, and product innovation. In this context, Takeda in June 2024 announced an investment of USD 230 million to expand plasma fractionation capacity at its Los Angeles manufacturing site, thereby adding up to 2 million liters of annual capacity.
Corporate Landscape of the Market:
Recent Developments
- In July 2026, Octapharma announced investment of USD 1.5 billion to build its first U.S. manufacturing facility in Rock Hill, South Carolina, creating a 50-acre biomedical campus. The facility will manufacture plasma-derived therapies as well as products supporting bleeding management, trauma care, and national emergency preparedness.
- In July 2025, Grifols announced investments in a new manufacturing facility in Lliçà de Vall, Barcelona, to double its plasma fractionation capacity in Europe and support more than 300,000 patients. The site will be connected to Grifols’ existing Parets del Vallès campus, thereby creating a 25-hectare biotechnology hub.
- Report ID: 4548
- Published Date: Aug 25, 2026
- Report Format: PDF, PPT
- Explore a preview of key market trends and insights
- Review sample data tables and segment breakdowns
- Experience the quality of our visual data representations
- Evaluate our report structure and research methodology
- Get a glimpse of competitive landscape analysis
- Understand how regional forecasts are presented
- Assess the depth of company profiling and benchmarking
- Preview how actionable insights can support your strategy
Explore real data and analysis
Frequently Asked Questions (FAQ)
About this Report
Connect with our Expert


Report, 2026-2035



Copyright @ 2026 Research Nester. All Rights Reserved.
