Rubber Process Oil Market Outlook:
Rubber Process Oil Market size was valued at USD 2.7 billion in 2026 and is projected to exceed USD 4 billion by the end of 2036, expanding at over 4.2% CAGR during the forecast period, i.e., 2027-2036. In 2027, the industry size of rubber process oil is evaluated at USD 2.8 billion.
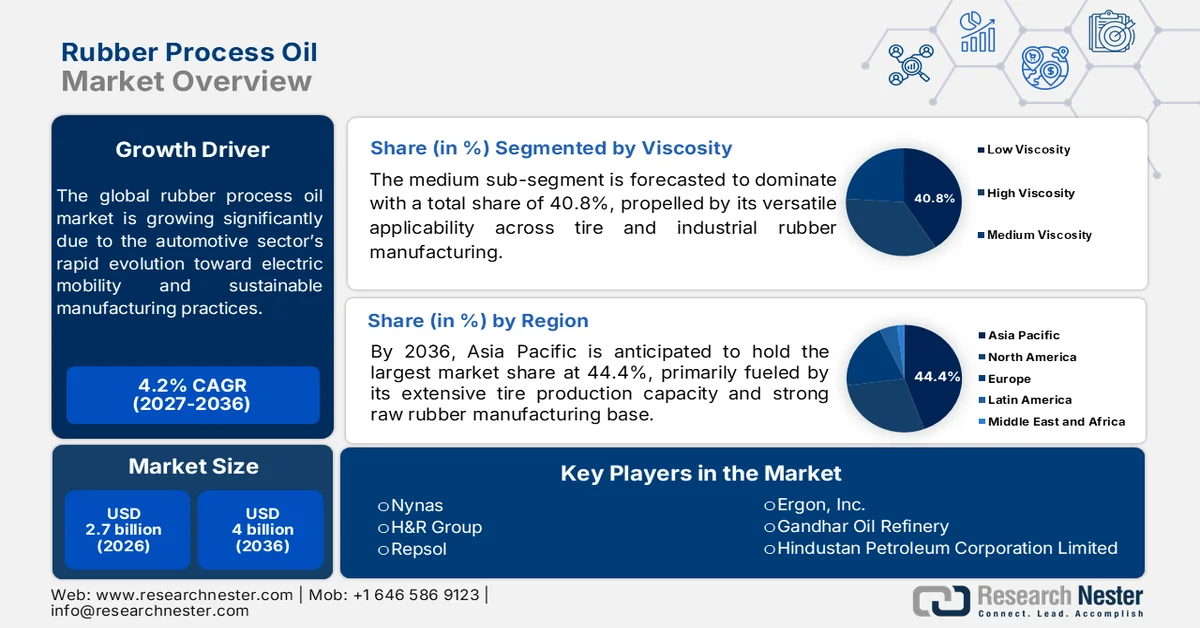
The global rubber process oil market is witnessing a profound structural transformation, which is driven by the automotive sector’s rapid evolution toward electric mobility and sustainable manufacturing practices. Market growth is primarily propelled by the escalating demand for high-performance tires that offer low rolling resistance, which compels a shift toward eco-friendly process oils and supports sustained activity across the global tire-retreading industry. This trend is reflected in international trade, with Germany leading retreaded rubber tire exports at USD 207.46 million in 2024 which was followed by Spain at USD 85.20 million, as stated by World Trade Integrated Solution (WITS). The presence of this strong export activity in major tire-producing industries indicates there is a heightened demand for rubber-processing materials, i.e., process oils, as manufacturers across different nations prefer sustainability and regulatory compliance.
2024 Global Retreaded Rubber Tire Exports by Country: Export Value and Volume
|
Exporting Country/Region |
Export Value (1000 USD) |
Export Quantity (Items) |
|
Germany |
207,458.98 |
851,986 |
|
European Union |
121,668.03 |
2,155,040 |
|
Spain |
85,202.51 |
736,845 |
|
Thailand |
78,368.75 |
266,160 |
|
France |
62,753.08 |
276,153 |
|
Belgium |
54,513.07 |
417,638 |
|
UK |
33,353.95 |
174,185 |
|
Netherlands |
30,394.51 |
431,668 |
Source: WITS
Upstream, this rubber process oil market depends on specific petroleum refining streams, which utilize heavier base oil fractions and vacuum distillates as primary raw materials to produce aromatic, naphthenic, and paraffinic compounds. The supply chain needs logistical integration, which links major oil refineries directly with chemical compounders and industrial rubber manufacturers. For instance, in December 2025, Ergon received the 2025 quality award from Pirelli, which is a recognition for its high-quality process oils and places it among Pirelli’s top seven suppliers out of 13,000 global suppliers. The company has partnered with Pirelli for four years, supplying process oils to five of its facilities, thus supporting high-performance tire manufacturing and rubber-processing applications.
Key Rubber Process Oil Market Insights Summary:
Regional Highlights:
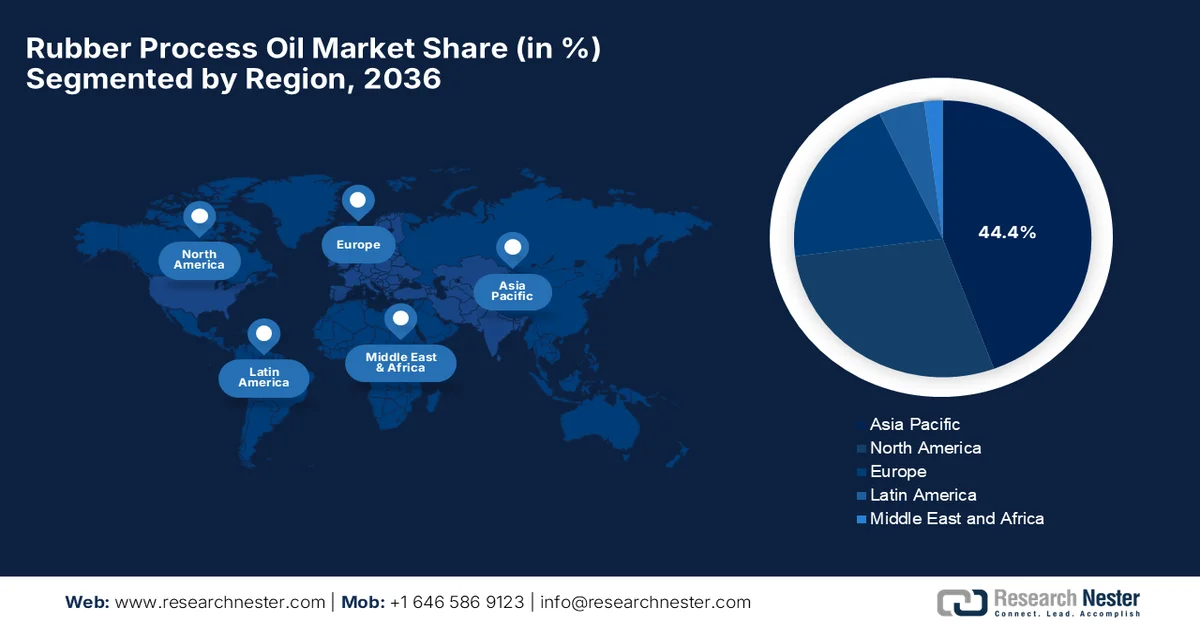
- Asia Pacific is projected to command the largest 44.4% share of the rubber process oil market by 2036, reinforced by its leading position in tire and raw rubber production, rapid automotive industry expansion, and extensive infrastructure development
- North America is expected to witness notable growth during the forecast period, supported by expanding end-use industries, stringent environmental standards, increasing electric vehicle adoption, and demand for low-rolling-resistance tires
Segment Insights:
- The medium sub-segment is anticipated to dominate the rubber process oil market with a 40.8% share by 2036, driven by its versatile application across tire and industrial rubber manufacturing, balanced processing characteristics, and efficient filler dispersion and compound mixing
- The tire sub-type is expected to capture a considerable share during the forecast period, owing to the high volume of global tire production, recurring replacement demand, and increasing requirements for fuel-efficient and high-performance tires
Key Growth Trends:
- Expanding automotive and electric vehicle production
- Surging natural and synthetic rubber production
Major Challenges:
- Stringent environmental and health regulations
- Extreme raw material and crude oil volatility
Key Players: Nynas (Sweden),H&R Group (Germany),Repsol (Spain),Ergon, Inc. (U.S.),Gandhar Oil Refinery (India),Hindustan Petroleum Corporation Limited (India),Witmans Industries (India),Sundrex (India),Taurus Petroleums (India),Pirelli (Italy),Pyrum Innovations (Germany),Synthos (Poland),Continental / ContiTech (Germany)
Global Rubber Process Oil Market Forecast and Regional Outlook:
Market Size & Growth Projections:
- 2026 Market Size: USD 2.7 billion
- 2027 Market Size: USD 2.8 billion
- Projected Market Size: USD 4 billion by 2036
- Growth Forecasts: 4.2% CAGR (2027-2036)
Key Regional Dynamics:
- Largest Region: Asia Pacific (44.4% share by 2036)
- Fastest Growing Region: Asia Pacific
- Dominating Countries: China, India, United States, Japan, Germany
- Emerging Countries: Indonesia, Vietnam, South Korea, Thailand, Brazil
Last updated on : 7 September, 2026
Rubber Process Oil Market - Growth Drivers and Challenges
Growth Drivers
- Expanding automotive and electric vehicle production: The global surge in vehicle manufacturing, especially electric vehicles, is considered to be the primary catalyst for the rubber process oil market. These EVs need durable tires to manage heavier battery weights and instant torque, which forces tire manufacturers to consume high volumes of advanced rubber process oils. In November 2025, the International Energy Agency stated that China’s car production reached a substantial 27 million in 2024, whereas India’s output rose 30% to nearly 5 million. It also mentions that electric vehicles exceeded 15% of global car production, thus supporting demand for advanced tire and rubber-processing materials.
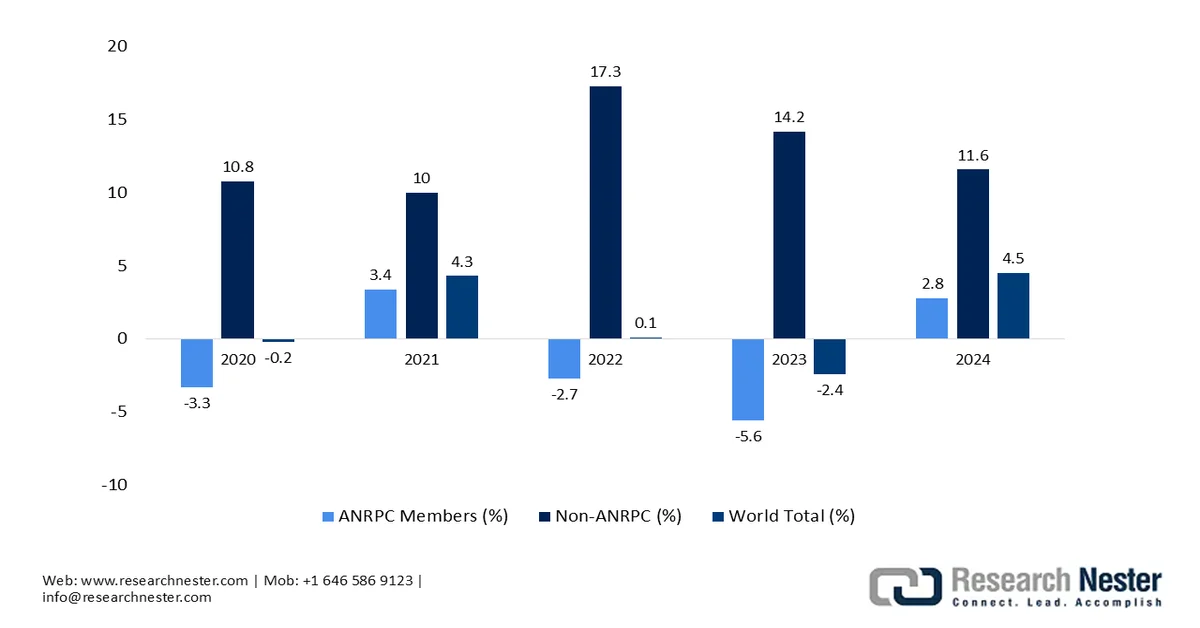
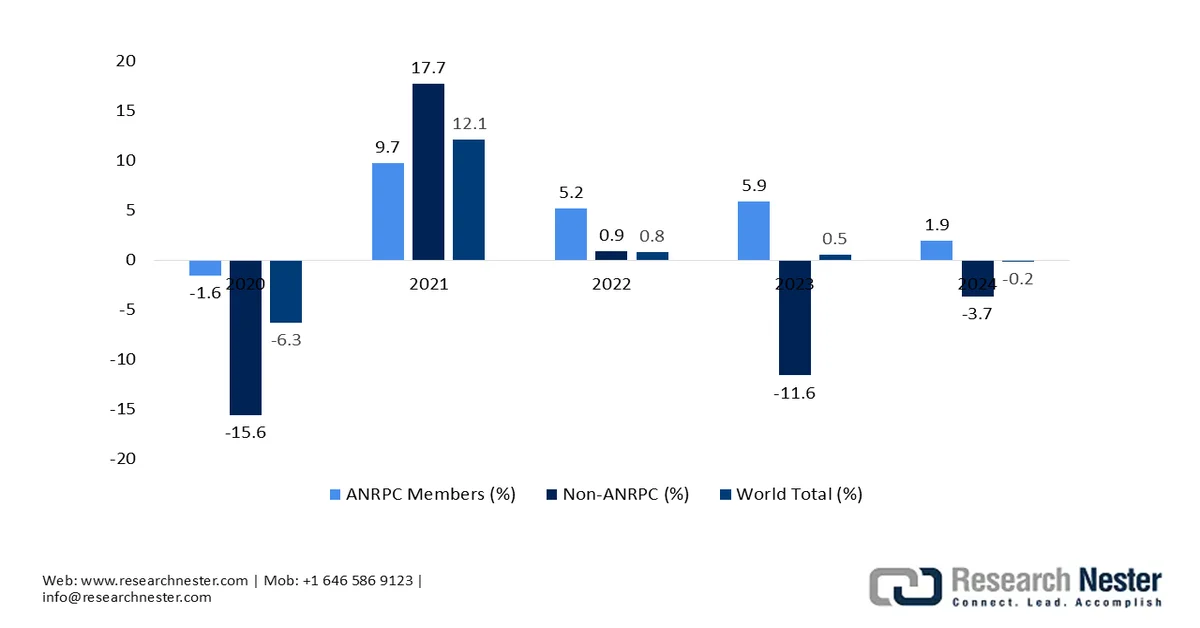
- Surging natural and synthetic rubber production: Globally, the rise in rubber production directly drives the consumption of process oils, which are highly essential for compounding raw polymers. As rubber plantation yields expand and synthetic rubber plants increase capacity, manufacturers require extreme volumes of process oils to soften compounds and improve processability, thus expanding the market for bulk oil suppliers. In November 2024, the Association of Natural Rubber Producing Countries (ANRPC) stated that global natural rubber production reached 11.2 million tons in the first months of Q4 2024, which is up 2.9%, while demand declined 4.5% to 12.1 million tons. Besides, these trends influence rubber processing costs and demand for rubber process oils in different applications.
Average Daily FOB Natural Rubber Prices by Grade and Key Market, September -October 2024
|
Rubber Grade |
Market |
September-24 (USD/kg) |
October-24 (USD/kg) |
% Change |
|
SMR-20 |
Kuala Lumpur |
1.96 |
2.06 |
4.92 |
|
STR-20 |
Bangkok |
2.03 |
2.14 |
5.53 |
|
RSS-3 |
Bangkok |
2.81 |
2.67 |
-5.04 |
|
RSS4 |
Kottayam |
2.74 |
2.37 |
-13.41 |
|
Latex |
Kuala Lumpur |
1.63 |
1.77 |
8.92 |
Source: ANRPC
Global Natural Rubber Supply Growth by Region, 2020 - 2024
Source: ANRPC
Global Natural Rubber Demand Growth by Region, 2020 - 2024
Source: ANRPC
Challenges
- Stringent environmental and health regulations: The rubber process oil market is witnessing growing challenges from stricter chemical safety regulations, especially those limiting products with high levels of polycyclic aromatic hydrocarbons. Regulations across different nations impose bans on traditional distillate aromatic extracts due to carcinogenic concerns about those chemicals. This forces tire manufacturers to switch to safer alternatives such as treated distillate aromatic extract and mild extraction solvate. However, this mandatory shift restricts production flexibility and creates severe supply bottlenecks. In this context, producers need to invest in new refining technologies and completely reformulate long-standing chemical structures, thus slowing overall market growth in strictly regulated zones.
- Extreme raw material and crude oil volatility: Rubber process oils are derived straight from petroleum refining streams, due to which the rubber process oil market is extremely vulnerable to crude oil price shocks. Geopolitical tensions and shifting production quotas cause fluctuations in feedstock costs, causing hindrance to market’s expansion. These rapid price swings undermine procurement strategies and destabilize profit margins. Small and mid-scale compounding businesses in this sector struggle the most, as they lack the financial buffer to absorb sudden upstream cost increases. In addition, refineries are shifting toward cleaner fuels and petrochemicals rather than specialty process fluids, which shrinks local feedstock availability, forcing rubber manufacturers to navigate through inconsistent material supply chains.
Rubber Process Oil Market Size and Forecast:
| Report Attribute | Details |
|---|---|
|
Base Year |
2026 |
|
Forecast Period |
2027-2036 |
|
CAGR |
4.2% |
|
Base Year Market Size (2026) |
USD 2.7 billion |
|
Forecast Year Market Size (2036) |
USD 4 billion |
|
Regional Scope |
|
Rubber Process Oil Market Segmentation:
Viscosity Segment Analysis
The medium sub-segment is forecasted to dominate with a total share of 40.8% in the viscosity segment by the conclusion of 2036. This dominance in the rubber process oil market is majorly propelled by its versatile applicability across tire and industrial rubber manufacturing, balanced processing characteristics, and ability to facilitate efficient filler dispersion and compound mixing. In addition, the booming production of automotive components, hoses, belts, seals, and other rubber products is sustaining demand for medium-viscosity grades. These grades of rubber process oil offer manufacturers a practical balance between processing efficiency, product performance, and formulation economics, thus denoting a wider segment scope.
Application Segment Analysis
On the basis of application, the tire sub-type is anticipated to capture a considerable share in the rubber process oil market during the stipulated timeframe. The segment is supported by the sheer volume of global tire production and the recurring replacement cycle of passenger and commercial vehicle tires. In addition, increasing demand for fuel-efficient and high-performance tires is encouraging manufacturers to optimize rubber formulations, sustaining consumption of process oils. In December 2025, U.S. tire shipments reached 337.4 million units in 2025, which is marginally above 337.3 million units in 2024. Apart from this, the growth in replacement tire shipments, particularly for light trucks, rose by 2.9%, and for trucks +7.9%, signaling continued demand for tire manufacturing and rubber-processing materials in the U.S.
U.S. Tire Shipments by Type and Application, 2024: Original Equipment and Replacement Tire Volumes
|
Segment |
2024 Shipments (Million Units) |
|
Original Equipment -Passenger |
43.1 |
|
Original Equipment -Light Truck |
6.7 |
|
Original Equipment -Truck |
5.7 |
|
Replacement -Passenger |
221.6 |
|
Replacement -Light Truck |
36.7 |
|
Replacement -Truck |
23.4 |
|
Total Shipments |
337.3 |
Source: USTMA
Type Segment Analysis
The aromatic rubber process oils segment, which is under the type category, is expected to capture a substantial share in the rubber process oil market over the forecasted years. The segment’s growth is majorly propelled by its strong solvency and compatibility with widely used elastomers, particularly styrene-butadiene rubber and butadiene rubber, which enables efficient incorporation of fillers and additives during compounding. Its established use in high-volume tire and industrial rubber formulations supports demand despite the gradual shift toward low-PAH alternatives. Moreover, their cost-effectiveness and processing efficiency make them an attractive option for manufacturers who are looking to optimize production costs, thus denoting a positive market outlook.
Our in-depth analysis of the rubber process oil market includes the following segments:
|
Segment |
Subsegments |
|
Viscosity |
|
|
Application |
|
|
Type |
|

Vishnu Nair
Head - Global Business DevelopmentCustomize this report to your requirements — connect with our consultant for personalized insights and options.
Rubber Process Oil Market - Regional Analysis
APAC Market Insights
Asia Pacific rubber process oil market is anticipated to garner the highest share of 44.4% in the global landscape by the end of 2036. The region’s leadership is mainly propelled by its position as the global epicenter for both tire production and manufacturing and raw rubber production. Market growth is primarily propelled by the rapid expansion of the automotive industry and massive infrastructure developments that drive the continuous demand for industrial rubber goods. In November 2024, Bridgestone announced an investment of USD 85 million to expand premium passenger tire production and development at its Pune and Indore plants in India. The Pune plant will add around 1.1 million tires of annual capacity by 2029, thus positively driving demand for rubber process oil.
The nation's rapid transition toward electric mobility and large-scale industrial modernization, which drive demand for highly durable, specialized rubber compounds, is an important growth driver for the rubber process oil market in China. On the other hand, upstream dynamics are supported by extensive domestic synthetic rubber refining capabilities and integrated supply chains, which allow for large-scale bulk procurement. Based on the government data published in November 2024, China’s annual new energy vehicle production surpassed 10 million units in 2024, marking a major milestone in the country’s transition toward low-carbon electric mobility. This compares with 9.587 million NEVs produced and 9.495 million sold in 2023, indicating continued expansion of China’s electric and new-energy automotive sectors, thus positively boosting demand for environmentally friendly process oils.
In India, the rubber process oil market is witnessing solid expansion, which is propelled by rising domestic vehicle ownership and state-led infrastructure projects. As a major global hub for tire manufacturing and industrial rubber goods, the country’s market benefits from a strong domestic supply chain which is closely integrated with expanding synthetic rubber production and a rising natural rubber cultivation footprint. In this context, IBEF in July 2025 stated that India’s rubber industry is expanding and is supported by 2.1% YoY growth in natural rubber production and 16.9% growth in synthetic rubber production in FY24. It also mentioned that the country’s rubber plantation area increased to 889,000 hectares, whereas exports rose to 4,199 tons in FY24, thus creating opportunities for rubber process oils.
India Rubber Production Trends: Natural and Synthetic Rubber Output FY19-FY25
|
Fiscal Year |
Natural Rubber Production (000 Tons) |
Synthetic Rubber Production (000 Tons) |
|
FY19 |
651 |
351 |
|
FY20 |
712 |
358 |
|
FY21 |
715 |
353 |
|
FY22 |
775 |
383 |
|
FY23 |
839 |
467 |
|
FY24 |
857 |
546 |
|
FY25 |
448 |
333 |
Source: IBEF
North America Market Insights
The North America rubber process oil market is growing at a notable pace owing to the growing end use industries and stringent environmental standards. Market demand is primarily propelled by the rapid integration of electric vehicles, which require low-rolling-resistance tires, along with a robust aerospace and industrial rubber goods sector. Upstream supply chains are highly integrated with the region’s massive petroleum refining infrastructure, which provides stable access to paraffinic and naphthenic base oils. North America also benefits from booming adoption of non-hazardous, eco-friendly chemical fluids, ensuring full compliance with strict regional safety regulations, thus making it suitable for standard market growth.
An exceptionally high per capita tire replacement rate and significant trade activities position the U.S. rubber process oil market for extensive growth. In addition, the market is structurally diversified by advanced commercial applications, experiencing a rapid influx of high-margin contracts for flexible flooring materials, performance adhesives, and rubber components which are utilized in the domestic aerospace and healthcare manufacturing industries. Trade dynamics reflect a balanced economic structure. In 2024, UN Data disclosed that the U.S. rubber industry maintains substantial international trade across both natural and synthetic rubber categories, reflecting strong activity in tire manufacturing and broader rubber-processing applications. The country depends on imports of natural rubber along with strong export flows of synthetic rubber.
U.S. Rubber Imports and Exports by Rubber Type, 2024: Trade Trends Supporting Rubber Process Oil Market Growth
|
Rubber Type |
Import Value (USD) |
Export Value (USD) |
Export Quantity (kg) |
|
Natural Rubber Latex |
51,547,896 |
10,206,388 |
3,417,877 |
|
Natural Rubber – Smoked Sheets |
248,669,101 |
14,668,203 |
6,278,160 |
|
TSNR |
1,513,047,781 |
39,694,233 |
17,426,667 |
|
SBR/XSBR |
628,843,184 |
508,978,312 |
- |
|
Butadiene Rubber (BR) |
104,684,742 |
470,802,236 |
247,773,282 |
|
Butyl Rubber (IIR) |
23,258,932 |
30,465,985 |
10,701,053 |
|
Halo-Isobutene-Isoprene Rubber (CIIR/BIIR) |
61,251,128 |
327,010,940 |
128,992,782 |
|
Chloroprene Rubber (CR) |
40,553,391 |
72,525,087 |
- |
|
NBR |
154,659,777 |
179,207,832 |
13,280,486 |
|
Isoprene Rubber (IR) |
25,877,734 |
102,912,881 |
28,133,755 |
|
EPDM |
155,064,378 |
525,536,964 |
229,188,966 |
Source: UN Data
The Canada rubber process oil market is reshaped by the country's extreme seasonal climate and its extensive primary resource industries. Market demand is largely driven by the mandatory and widespread consumer transition to specialized winter and all-weather tires, which need unique rubber formulations that maintain flexibility and traction in sub-zero temperatures. In addition, Canada’s market relies on heavy-duty industrial applications, consuming significant volumes of process oils for the production of mining conveyor belts, agricultural machinery hoses, and oilfield rubber components designed for rugged terrain. Apart from this, environmental stewardship is integrated directly into procurement pipelines, wherein the country’s manufacturers proactively collaborate with domestic forestry and agricultural biorefineries to pioneer the commercial blending of bio-sourced process oils.
Europe Market Insights
The Europe rubber process oil market is forecast to expand at a considerable rate, which is propelled by the circular economy and advanced chemical safety standards. Market demand is strongly driven by stringent environmental labeling laws for tires, which mandate high wet grip and low noise ratings, along with a rapidly growing market for retreaded commercial vehicle tires. As of December 2023 data, Europe generates around 300 million end-of-life tires annually, with a large share still sent to landfills or incineration, creating a need for more sustainable recycling solutions. Therefore, the LIFE GREEN VULCAN project developed an environmentally friendly devulcanization process to recover rubber from discarded tires for use in new tire treads and automotive components, thus making it suitable for standard rubber process oil market growth.
The presence of leading global premium tire manufacturers and premium original equipment manufacturers requires hyper-customized oils, which is an important factor driving growth in the Germany rubber process oil market. In this country, innovation focuses heavily on co-developing smart, sensor-embedded rubber compounds and advanced noise-reduction materials that require specialized paraffinic and naphthenic carrier fluids. Trade dynamics are highly localized within the region’s freight corridors, relying on a sophisticated network of rail and barge transit along the Rhine to manage bulk chemical imports and exports. On the other hand, domestic pricing structures are heavily influenced by stringent national energy-efficiency mandates and localized chemical park operating costs.
The UK rubber process oil market is capturing significant growth opportunities owing to the increasing adoption of specialty and sustainable formulations. Demand is also benefiting from the development of high-performance rubber compounds, and an expanding focus on circular manufacturing is creating additional opportunities for recycled and tire-derived feedstocks. In June 2026, the UK Environment Agency introduced a framework defining when tire pyrolysis oil (TPO) produced from waste tires can achieve end-of-waste status and enter regulated markets. It also mentioned that TPO must use approved tier waste, meet specified quality criteria, and be supplied to a suitably permitted refinery with a confirmed use as feedstock.
Key Rubber Process Oil Market Players:
- Nynas (Sweden)
- H&R Group (Germany)
- Repsol (Spain)
- Ergon, Inc. (U.S.)
- Gandhar Oil Refinery (India)
- Hindustan Petroleum Corporation Limited (India)
- Witmans Industries (India)
- Sundrex (India)
- Taurus Petroleums (India)
- Pirelli (Italy)
- Pyrum Innovations (Germany)
- Synthos (Poland)
- Continental / ContiTech (Germany)
- Company Overview
- Business Strategy
- Key Product Offerings
- Financial Performance
- Key Performance Indicators
- Risk Analysis
- Recent Development
- Regional Presence
- SWOT Analysis
- Nynas is a leading manufacturer of naphthenic tire and rubber oils, and it is offering NYTEX® and NYFLEX® grades for tires, industrial rubber, and TPE applications. The company’s strengths include broad polymer compatibility, customized formulations, and global availability.
- H&R Group is s a key industry participant which is offering specialty process oils designed for use in tires, natural rubber, plastics, and various industrial applications. Besides, the firm’s competitive strengths include a broad product portfolio and a well-established Europe manufacturing presence.
- Repsol supplies rubber process oils including aromatic extender oils and paraffinic grades such as EXTENSOIL. The company is highly focused on product performance and sustainable solutions for rubber and tire manufacturers.
- Ergon, Inc. offers naphthenic and paraffinic rubber process oils under its HyPrene® brand, which are suitable for tire, rubber compounding, hoses, belts, and polymer applications. The firm’s main strengths include product variety and global reach.
- Gandhar Oil Refinery manufactures aromatic, paraffinic, naphthenic, and low-PCA rubber process oils under its Divyol brand. The company primarily benefits from a broad portfolio, customized products, cost competitiveness, and growing international presence.
Here is a list of key players operating in the global rubber process oil market:
In the global rubber process oil market, competition is primarily driven by established specialty-oil and petroleum manufacturers that are offering broad portfolios of naphthenic, paraffinic, aromatic, and low-PCA grades. Leading manufacturers in this sector differentiate through product consistency, high-end technical performance, global production capabilities, and customized formulations which are suitable for tire and industrial rubber applications. In this context, FARREL POMINI in January 2026 acquired majority ownership of WF RECYCLE-TECH to accelerate the global commercialization of patented tire pyrolysis technology. This technology uses FARREL POMINI’s farrel continuous mixer to convert end-of-life tires into valuable materials such as recovered carbon black and oil.
Corporate Landscape of the Rubber Process Oil Market:
Recent Developments
- In July 2026, Pirelli, Pyrum, Synthos, and BASF launched a tire-to-tire recycling initiative in Europe to convert end-of-life and scrap tires into recycled materials. Pyrum uses pyrolysis to produce recovered carbon black and tire pyrolysis oil, which are processed into certified circular raw materials.
- In September 2025, ContiTech invested in advanced pyrolysis technology to recover valuable raw materials from complex waste rubber and reduce reliance on fossil resources. This new pilot facility purifies pyrolysis oil and thereby enables its potential reuse as a feedstock for producing new rubber and plastic materials.
- Report ID: 5222
- Published Date: Sep 07, 2026
- Report Format: PDF, PPT
- Explore a preview of key market trends and insights
- Review sample data tables and segment breakdowns
- Experience the quality of our visual data representations
- Evaluate our report structure and research methodology
- Get a glimpse of competitive landscape analysis
- Understand how regional forecasts are presented
- Assess the depth of company profiling and benchmarking
- Preview how actionable insights can support your strategy
Explore real data and analysis
Frequently Asked Questions (FAQ)
About this Report
Connect with our Expert


Report, 2027-2036



Copyright @ 2026 Research Nester. All Rights Reserved.
